Mix vies of NYC and graphs

Is that “angel investor” actually a demon in disguise?
angel investor

You’ve seen them on TV — those sharp-dressed, smooth-talking angel investors with big personalities and even bigger wallets. Sure, they’re charming and have the business chops to prove their success. But are the sharks and dragons of the world actually the right people to partner with in your next business venture?

Yes, due in part to the smash hits Shark Tank and Dragons’ Den, angel investors can be a consideration when startups and small businesses look for funding. In fact, the typical angel investment can provide $25,000 to $100,000 of funding — a significant stake in your business. Is that investment worth its value, and are there hidden costs or risks associated with this new business relationship?

There’s no doubt that many angel investors can bring incredible experience to the table. They know how to grow a company, have savvy business minds, never fear the unknown and have a wonderful ability to take on what others may see as a risk. Compound all those traits with their deep pockets and you’ve got a recipe for huge returns.

However, not all angels are watching out for your best interest. Keep your eyes peeled for these six types of angel investors that may actually be demons in disguise.

The Tire Kickers

You likely need fast funding and don’t have time to waste with investors who aren’t serious about committing funds. This isn’t a used car lot, so watch out for “The Tire Kickers.”

“As a founder, the last thing you need is to have your chain yanked. A firm “no” is far better than “we’ll think about it” or “we’ll take it under advisement.” If you feel like an angel is stringing you along, trust your gut,” advises Jenny Q. Ta in Fast Company. “Chances are pretty good they are afraid of making a commitment until they know who else is joining the round. Beware of the sheep in angel’s clothing.”

The Sharks

You’ve undoubtedly seen this personality shine on the reality shows. A would-be entrepreneur pitches their product, but can’t recall every financial figure and stat to back their claims. That’s when “The Sharks” see their prey — and they attack.

According to Martin Zwilling in Business Insider,“This is the ultimate bad guy whose sole intention of getting involved in early-stage investing is to take advantage of what they believe is the entrepreneur’s lack of financial and deal-making experience. If the term sheet process turns to pure torture, it may be time to respectfully bow out.”

The Overachievers

Angel investors are naturally more risk tolerant, and they may expect you to be as well. With high risk comes the potential for higher returns, and “The Overachievers” are going to want to see the money. Be prepared for these angels to expect bigger payouts than the average investor.

“It isn’t unusual for an angel investor to expect a rate of return that equals 10 times their original investment inside the first 5 – 7 years,” states Murray Newlands with Startup Grind. “When you are being held to this type of standard, the pressure to generate may be intense. If you are considering angel investors, you must determine whether the startup is within a position to expand at the rate the investor expects.”

The Archangels

Every good angel has a mentor, and these higher-ups are called “The Archangels.” They can bring other investors together and make deals happen fast. The Archangels can shape any idea, organize creative funding agreements and turnaround entire companies. These angels are the key contacts that everyone wants to be in touch with, and for good reason — since their influence can attract would-be investors from other industries and geographies. But be warned, as certain Archangels aren’t so trustworthy…

“There are a lot of people that pretend to be «Archangels» and offer to connect you with people that have money, sometimes for a fee,” says Todd Vernon in a recent Inc. article. “If your «Archangel» Investor is not actually investing his or her money, but simply acting as a proxy for others, take note; that is a warning sign.”

The Know-it-alls

Experienced angels have often been in the game for years, and many of them have grown their own companies by completely disrupting their industries with innovative products and methodologies. But in some cases, this is a breeding ground for “The Know-it-alls.” Because these people have been uber-successful by forging their own paths, they may now believe that their way is the right one. And it can be hard for The Know-it-alls to let go and allow you to chart your own territory.

The trick is dealing with this type of angel in a particular way, as Jonathan Moules explained in a Financial Times article. “Be diplomatic about how you receive an angel’s advice, adopting the tips on more “timeless” matters – such as how to find a good salesperson or how to launch a product – and politely ignoring the advice on matters specific to the investor’s previous forays into business.”

The Control Freaks

Although you might be looking for a hands-off investor, be assured that most angels still need to be involved in certain parts of how your company is run. “The Control Freaks” take this to a whole other level though, looking at every detail of how you run your business with a microscope, and then micromanaging to ‘tell’ you how to move the business forward.

“Angel investors aren’t going to shell out big bucks without taking an interest in how the money is used. If you’re expecting them to take a completely hands-off approach, you may be in for a rude awakening,” cautions Rebecca Lake at Quickbooks. “It’s more likely that your angel will want to take an active role in making decisions that affect the outcome of your business.” Lake warns that even with “The Control Freak” making decisions on your behalf, you are still accountable. “Even if they leave the reins in your hands, you’ll still be accountable for explaining the reasoning behind your choices.”


If you’re looking for investors and enhanced business funding, angel investors can still be an option. Do your homework and due diligence to know exactly who you’re working with, understand their expectations and make the right funding partnership. And if the agreement isn’t sitting well with you, don’t sign on the dotted line until you’ve looked at all your options.

There are always alternatives to secure funding for your business, like with Liquid Capital Factoring or Asset-Based Lending. Feel free to reach out and we can discuss your options.
Group of businessmen on top of a mountain illustration

How to build one of the best sales teams in the world

teamwork

“Coming together is a beginning. Keeping together is progress. Working together is success.” –Henry Ford

Team building is an ongoing process for large and small businesses alike. The right team can be the difference between success and failure, or scalability and stagnation.

Sales people are empowered entrepreneurs, but they can also build a team around them to support their professional and personal goals — and that approach can help them strategically fast track their next moves. Let’s take a look at how the right approach to team building is just as important to growth as the right working capital.

Great leaders build great teams

“Rome wasn’t built in a day,” and it sure as heck wasn’t built by one person.

Great leaders are the lifeblood of great teams, but that doesn’t happen by accident. So it helps to understand the ways in which teamwork is literally wired into our brains.

There is a fundamental importance of rewarding your team’s ‘collective success’ versus just the ‘individual performance.’ Psychology Researchers and Neuroleadership experts Jay Van Bavel and Dominic Packer revealed in the Harvard Business Review why focusing on collective success makes all the difference.

“Although leaders are concerned with collective success, most organizations — from sports teams to universities to global companies — still focus on rewarding individual performance. The majority of Fortune 500 companies reward the most productive individuals, not the most effective groups or indispensable group members. We believe that leaders at these organizations are overlooking something fundamental about human nature — our tribalism.”

Buck your traditions

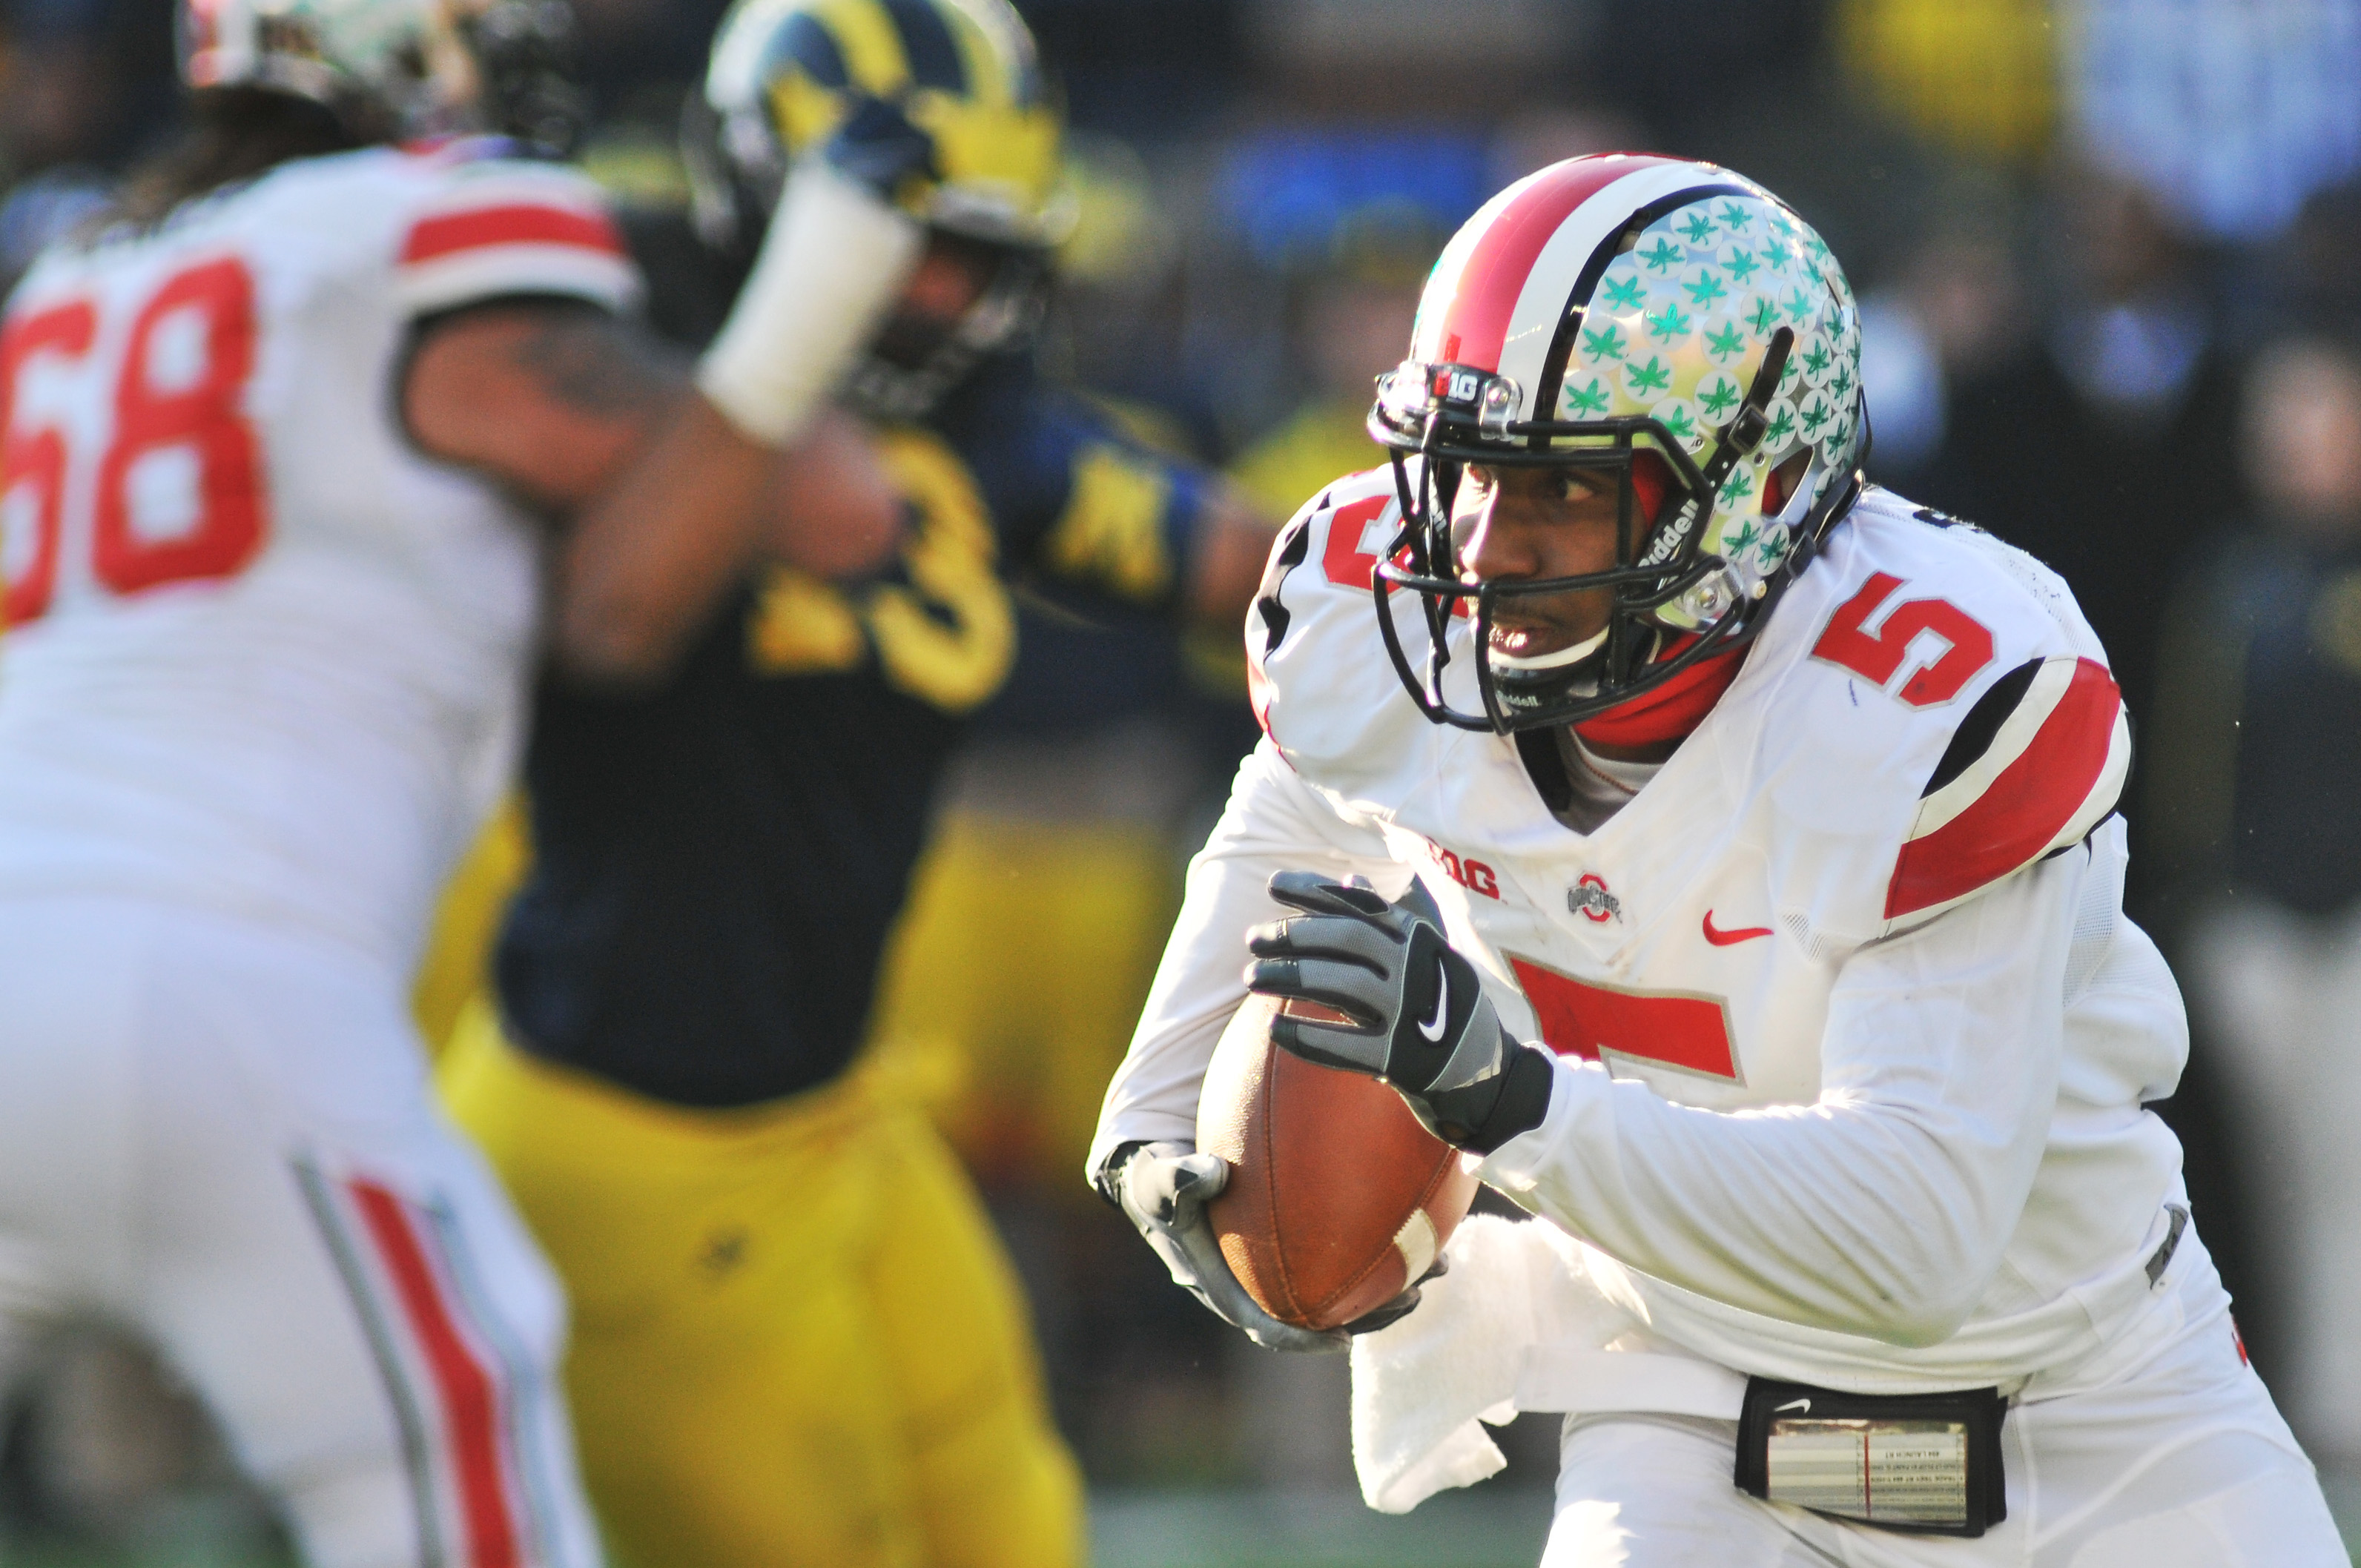
Van Bavel and Packer led their research with an example of a nearly 50-year old Ohio State Buckeyes football tradition — and it’s the reward system behind all those Buckeye stickers on players’ helmets (you know, the ones that look like little hemp leaves — both amusing and beneficial).

Buckeyes

So what’s the story behind this?

In 1968, the Buckeyes coaching staff wanted to reward exceptional plays and encourage their team to keep winning — and so a new tradition began. Individual players were rewarded with Buckeye stickers to place on their helmets — a visible reminder of their success. The system paid off in spades, and the team won the championship that year. They continued a dominating streak in the league, but it wasn’t ever lasting. Over the next few decades, the system was failing and the team was, too.

In 2001, a new head coach flipped the way players earn Buckeyes. Instead of their old system of rewarding a player for scoring a touchdown or other individual victory, every player on the offensive unit would get a sticker if the team scored more than 24 points.

The purpose? The idea of favoring teamwork over individual performance was the real goal. And it paid off almost immediately. The team not only won a national championship the following year, but the Buckeyes have been one of the most successful teams in the country ever since.

Your team members want to fit in

Belonging to a group is a deeply rooted aspect of who we are as individuals. Van Bavel and Packer further explained how managing this mentality is a major role that leaders will play.

“Great leaders are “entrepreneurs of identity.” They embrace our tribal nature and seek to shape the identity of fellow group members,” they elaborate. “Human beings evolved in groups, and most of us still work in groups every day. … This is why sports fans can show up to a stadium and immediately share a common purpose with 100,000 complete strangers.”

That might be the case at a sports stadium, but how about at the workplace? The researchers clarify that it is quite similar.

“When a person starts to identify with a group, it triggers a fundamental shift in their goals. Events and decisions that were once evaluated with reference to oneself (“what’s in it for me?”) are now evaluated in reference to the group (“what does this mean for us?”).”

That shift to a healthy team mentality is one of the most important psychological breakthroughs a company can have.

Does your team feel safe?

What’s more, business leadership expert Chee Tung Leong illuminated the fact that today’s average lifespan of an S&P 500 company has fallen from 67 years to just 15 years.

“The marketplace is much more unforgiving towards companies that take too long to learn their lessons,” Leong explained. Creating a culture of learning at your company is key to success.

As entrepreneurs, we talk a lot in business about the virtues of bold thinking and risk taking, but what Leong uncovered while studying team dynamics at Google, is that you must create an atmosphere where people feel comfortable taking those bold chances.

Chief among these key dynamics was this idea of ‘psychological safety.’ To build the best teams in the world, Leong explains that “team members needed to feel safe enough to take risks and be vulnerable in front of each other.”

“While self-preserving behavior is natural in the workplace, it can erode the foundation of effective teamwork.” This can damage the culture you are trying to build – where team members can learn from one another. “The safer team members feel with each other, the more likely they are to collaborate, admit mistakes, and take new opportunities.”

Leong advocates building the culture of psychological safety on your own teams through three fundamentals:

  1. Encourage failure
  2. Admit your own mistakes
  3. Hold “anxiety parties”

The latter, while admittedly unconventional, allows team members to openly share things that make them feel vulnerable and anxious, allowing for immediate 360-degree feedback with the team. Leaders can then address issues head-on and avoid wasting time on assumptions about the team’s feelings — instead, focusing on the real problems at hand.

Transform your clients into your teammates

Taking this strategy a step further, as a leader you can encourage your team to look outside the organization. Sales experts Barry Farber and Robert L. Shook argue that one of the most effective yet overlooked sales techniques involves teaming up with customers.

“Outsource your customer. Let the customer solve problems for you,” explains Shook and Farber. “A salesperson’s job is to create a vehicle that lets the customer solve his or her own problems.”

This out-of-the-box thinking can take your sales organization to a new level. “When a customer becomes involved in finding a solution to his problem, he or she takes ownership, which is the foundation of a solid salesperson-customer relationship.”

At the end of the day, a winning teamwork philosophy is one that encourages both parties to work together to solve a mutual problem. The best teams are as unique as you and your company, and making these proven team building concepts parts of your company’s direction will serve everyone well.

A swimmer and a shark illustration

What is Fintech Stacking & Why You Need to Avoid It

Why unsecured loans are eating away at many company’s bottom lines.

fintech loans

It seems like a less than savoury business practice – companies resorting to fraudulent activity to access tens or hundreds of thousands of dollars, often just to cheat the system. Taking out multiple online loans from new fintech companies who offer almost-instant cash, borrowers prey on a new financial system based entirely on unsecured loans.

This is “loan stacking,” and it’s hitting the fintech industry hard. The bigger problem is that it’s also crippling the companies in need of real funding.

What is loan stacking?

According to the Lending Times, loan stacking occurs when a consumer secures multiple loans of the same type from different financial institutions – and it is also one of the main types of financial fraud. This is an obvious problem for the lenders, but also a highly risky game for the borrower.

Although reputable business owners may indeed be shopping for multiple loan options, most stacking is associated with being intentionally deceitful. In the latter case, the borrower takes advantage of time lags in the credit bureau reporting, with no intention of paying the lender back.

In fintech, this issue can be exacerbated, since their “soft credit checks” and online loan approvals typically take less than 24 hours – not enough time for a lender to realize the borrower just requested similar loans from other institutions. Between 2013 and 2015, such occurrences in the market nearly doubled, causing fintech underwriters to ring serious alarm bells.

Why are some businesses stacking loans? And are these people really criminals?

According to a recent USA Today article, only one in five small business owners in need of financing will get approved by a traditional bank. According to Nonso Maduka from the financing comparison website NerdWallet, “that leaves 80% who can’t get funding from a traditional bank source, even though that’s likely the lowest cost.” This is why it’s important to keep yourself up to date on all Fintech news and information.

If traditional bank loans aren’t an option, these companies will be forced to look elsewhere and find creative solutions to their funding woes. Maduka goes on to explain some of the major challenges forcing companies away from the traditional system. “If you’ve gone through the process of applying for a bank loan and aren’t eligible, you haven’t been in business long enough, the amount of money you’re requesting is less than $500,000, if you’re thinking about speed, or just need cash in order to keep moving, an alternative lender might be a good option.”

After the 2008 crash, business funding dropped dramatically, making access to that capital much more challenging. And by 2014, the number of loans was down nearly 60 per cent from its peak in 2007, according to the Woodstock Institute’s report on small business lending.

It’s apparent that there’s a massive need for funding in the business community – to grow more rapidly, hire employees and make investments. But there’s an equally apparent shortage of options for many companies, forcing them to get creative.

That doesn’t mean that all companies obtaining multiple loans are deceitful – far from it. There are countless hardworking, honest business owners that are in search of higher working capital to keep their companies afloat and growing in the right upward direction. And obtaining multiple loans is possible if you’re being transparent with the lenders. But stacking loans is not a viable solution.

The true offenders are the “borrowers” intentionally preying on this system, posing as credible business owners. This could have the adverse effects of raising fintech costs, slowing down lending cycles and making it even more challenging for legitimate borrowers to access capital in the future.

The astronomical costs of fintech loans: Are they to blame?

For the fortunate business owners that can access traditional loans or leverage their personal assets including home equity, property or other investments, finding cash flow may not be the biggest issue. But when these options aren’t available, other businesses may turn to fintech and other unsecured loans – supported by creditworthiness, rather than collateral. The Globe and Mail pointed to discussions at The Future of Lending Now conference, which stressed that unsecured fintech lending, “opens the floodgates to increased risk of fraud and more personal and business bankruptcies.”

Taking on fintech or other unsecured loans can get businesses out of sticky financial situations, but they aren’t long-term solutions. Most unsecured loans like credit cards, revolving loans, personal lines of credit, payday lenders and merchant cash advances come with steep interest rates to protect the lender. For business owners, stacking debt and taking on multiple loans to hit their desired level of capital, the impacts can be shockingly unexpected.

Even though obtaining such a loan could bring immediate relief, Woodstock Institute cautions against such activity, citing dissatisfaction from those same borrowers. In fact, their study found that, “high interest rates, onerous terms, and relatively poor customer service are unfortunately common among such providers.”

368% interest rates

Looking directly at the hard numbers, Woodstock Institute’s analysis found that the interest rates for such fintech loans can start at 26% and go up to an astronomical 368%. Compare that to the current traditional bank loan in the range of 6.5 to 9% and you’ll see why dissatisfaction amongst borrowers could skyrocket.

This is where stacking and refinancing really becomes a problem. When a company is in that deep, the problem has become how they’ll pay off such exorbitant interest rather than paying down the original debt. The focus shifts away from their business operations and strategy – the original intention of the loan.

Opportunity Fund, a US-based non-profit lender and organization tackling economic inequality, also offers “microloans” to business owners in need of assistance – including those that have been handcuffed by their fintech loan. In fact, after analyzing 150 of businesses needing refinancing on their fintech loans, they found the companies were paying an average interest rate of 94%, with a high of 358%. The average monthly payment on those loans was 178% of the borrower’s available net income. This leads to financial instability for the business and their personal assets. “Every month these borrowers owed more to the lender than they had available from both business and personal net income.”

Multiply that disastrous impact even further if a business was stacking their loans or taking on multiple fintech debts, and that could spell complete financial ruin and bankruptcy.

Better funding options to avoid the pitfalls

Avoiding high interest and unsecured loans altogether is one option that some business owners have taken.

That’s where financial products like Asset-Based Loans (ABL) enter the picture and fill a much-needed gap. For companies who don’t meet the qualifications of a traditional bank loan, or simply don’t want to go that route, they can obtain a loan or line of credit that is secured against their company’s assets. With such a loan, assets can include accounts receivable, equipment, inventory or real estate. Timing of ABL loans can take longer than an unsecured option, largely because of the due diligence process that reviews the borrower’s financials and collateral. However, only a week or two is needed to establish a trusted relationship with the ABL lender and access capital.

For Asset-Based Lending, funding levels are based on the value of the available company assets, and the lender will assign a loan-to-value (LTV) – a percentage that the business can borrow against. For well-established businesses, this provides much more flexibility than unsecured options. Although lending amounts are typically higher for ABL, the solution can provide the business incredible amounts of capital – sometimes up to $10 millions in funding. As for ABL rates, although they can be higher than a traditional bank loan, they are substantially lower than average fintech loans, and are far more stable.

ABL delivers a variety of additional benefits:
  • Improved customer optics – your ABL solution is invisible to the end customer
  • Leverage multiple asset categories to generate extra capital as required
  • Rates are lower than fintech loans or a pure factoring solution
  • Available borrowing amounts are typically calculated weekly (not monthly as with a bank) so if you’re in a strong growth cycle, your ability to borrow increases more quickly

But ABL isn’t the only option available.

Transform your customer invoices into quicker cash flow

For less established or smaller business, other options like accounts receivable financing (also known as factoring) can come into play. By leveraging incoming invoices, a company can gain almost-instant cash flow without the risks associated with unsecured fintech loans. In these situations, a factoring company will purchase a business’ accounts receivable and provide immediate payment, holding back a small reserve fee. Because this is a less strenuous process and doesn’t rely on company collateral, the timing is also notably faster than ABL to access capital.

The transaction can have the resemblance of a business line of credit, although it is technically a sale of accounts receivable, and in some cases the fees are even deductible. Factoring fees are typically higher than ABL, but are once again substantially lower than unsecured options with significant penalties. Since they are based on incoming accounts receivable, businesses also are not struggling to make their factoring payments, as the funds come directly out of the collections on those invoices.

When presented with both options, a company will generally lean towards ABL due to its flexibility. Either way, compared to the unsecured options and high-interest fintech loans, it is in a business’ best interest to investigate and compare all their options before taking on unnecessarily stacked levels of debt.

Financiamientos Recientes – Septiembre 2017

Logo

Brechas generacionales en los negocios: el abismo de los milenios

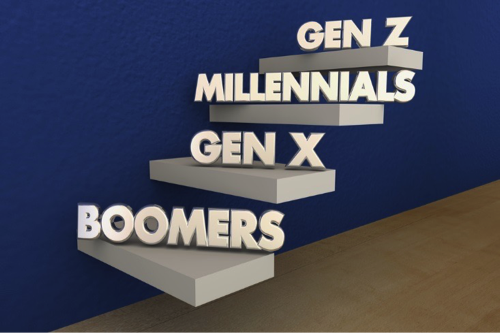
Ser empresario, empleador o dirigente en el mundo de los negocios de hoy en día requiere estar al tanto de las necesidades de todas las generaciones que integran su personal: los Baby Boomers y las generaciones X, Y y Z. No importa que se trate de su personal, de sus clientes o des sus accionistas, comprender las diferencias entre los valores y las motivaciones de cada una de estas generaciones hará que su empresa funcione de manera más eficaz y que, en últimas, se aumenten las ganancias netas.

El cambio es inevitable… y está ocurriendo aún más rápido que nunca antes

Mientras que las generaciones anteriores le temían al cambio y estaban determinadas a conservar el orden establecido, para los mileniales y la nueva generación Z el cambio es emocionante y normal.

Ciertas generaciones han causado más polémica que otras. Hoy, son los mileniales (también conocidos como la generación Y) que han ganado mala prensa. Dignos de derechos, ensimismados y sin enfoque son los adjetivos típicos que navegan por el océano de la negatividad con la que se describe a la generación de nuestra mayoría de recursos humanos. No pueden vivir sin sus celulares, han crecido jugando videojuegos y esperan gratificación inmediata. Muchos afirman que esta generación no puede tomar una decisión sin consultarla con todos sus conocidos. Otros dicen que son absolutamente perezosos y que esperan que se les respete simplemente por hacer acto de presencia.

¿Todo esto suena familiar?

Pues debería, ya que críticas igualmente duras de cada nueva generación han circulado desde el final de la Segunda Guerra Mundial. Pensemos no más en el pánico de los padres cuando Chubby Checker se hizo popular. ¿Recuerda a los «rebeldes» creados por los Beatles? ¿Y qué decir del sacrilegio de haber quemado las tarjetas de alistamiento? Los jóvenes advenedizos han causado caos con el paso de cada generación, y por eso debemos estar absolutamente agradecidos.

Cada generación trae con ella innovaciones que modelan nuestro futuro, y el liderazgo de usted como dirigente puede marcar una gran diferencia.

El liderazgo estratégico puede apaciguar cualquier circo

Como se explica en el libro Confident Leadership in 21st Century Business: Bridging the Generation Gaps, asumir un rol de liderazgo en el mundo de los negocios de hoy es como ser el maestro de ceremonias de un circo. Con tantos artistas y actos en el escenario, el maestro de ceremonias debe reconocer los talentos de cada uno de ellos y proporcionarles las herramientas que necesitan para dar un buen espectáculo.

Asimismo, un líder empresarial debe reconocer las diferentes generaciones que conforman su equipo y modificar las herramientas y tácticas para trabajar con cada una de ellas. El rol de un líder incluye también descubrir lo que caracteriza cada generación y utilizar esa información para canalizar sus habilidades.

En los negocios, el buen líder es consciente de que la generación X prefiere la información que ha sido cuidadosamente filtrada, que la generación Y se nutre de tutoría y elogios y que la generación Z que viene necesita entender de qué manera sus funciones encajan en el conjunto.

Creamos las cualidades de la generación Y

Sin embargo, mientras algunas personas puede que vean a la generación de los mileniales como exigente y reclamadora de derechos, no olvidemos que esta generación fue criada de manera diferente a la generación anterior.

Les otorgábamos trofeos incluso cuando perdían y los elogiábamos por cualquier actividad que emprendían. Al comprarle a esta nueva generación cantidades de aparatos electrónicos, les enseñamos a conocer el mundo de respuestas rápidas y a obtener información inmediata con un chasquido de dedos. Aprovecharon todas las oportunidades para aprender el complejo mundo de los computadores, y los felicitamos por su ingeniosidad para resolver problemas en un abrir y cerrar de ojos.

Los estilos de comunicación han cambiado, y a medida que la generación Y empezó a entrar en la adolescencia, el mundo basculó sustancialmente hacia una nueva dirección, con cambios sin precedente como los que se vivieron durante la Revolución Industrial. Les dimos celulares para permanecer en contacto con ellos, teléfonos inteligentes con acceso instantáneo a Internet y computadores por todas partes a donde iban. Ellos aprovecharon esa tecnología para aprender a adaptarse rápidamente y para estar en contacto con el mundo y con sus semejantes en todo momento.

Generación Z: Una nueva generación con impacto en los negocios

La generación Z no conoció el mundo sin celulares, sin accesorios de mano y sin aparatos conectados a Internet. Ellos están creciendo en un ambiente de inestabilidad económica e institucional, están siendo afectados por el agotamiento de recursos y los cambios climáticos, y están conectados con el mundo entero mediante las redes sociales. Tienen siempre la información al alcance de la mano, son expertos en tecnología y análisis, y están cambiando la manera de hacer negocios en el mundo. Ni siquiera los mileniales podrán entender fácilmente este nuevo giro.

Los jóvenes van más allá de las fronteras; eso es lo que todas las generaciones anteriores a ellos han hecho, y eso es bueno. Les hemos enseñado a no tener miedo de ensayar nuevas cosas; los hemos animado a descubrir formas innovadoras para alcanzar sus objetivos. Esta generación es brillante. Los líderes empresariales verán que encaminar a la generación Z para que encuentre el lugar que le corresponde en la organización permitirá aprovechar sus conocimientos y entusiasmo, generando a la larga resultados y mejores beneficios.

Sí, es difícil dirigir personas que saben más que nosotros y, sí, esta generación hace las cosas de manera diferente a nosotros. Aunque los recuerdos de la vida sin teléfonos celulares y computadores personales afloran de vez en cuando, es difícil imaginarse dirigir hoy una empresa sin estas herramientas. Aún están por venir fantásticas posibilidades, cuyas ideas vendrán sin duda de las generaciones de empleados más jóvenes.

Forme, guíe y tenga cuidado de no micro-administrar a esta generación. Al contrario, agradezca el valor de las generaciones que traen cambios.

Autora y conferencista en el campo de los negocios, Rosemarie Barnes resalta las dificultades que los dirigentes pueden tener que afrontar al tener múltiples generaciones en un lugar de trabajo. Lea más acerca de la forma en que las brechas generacionales en el campo de los negocios están afectando la salud y ganancias de las empresas en su libro: Confident Leadership in 21st Century Business: Bridging the Generation Gaps, ahora en venta en Amazon (USA y Canadá). Se puede reservar a Rosemarie para hacer presentaciones por rbarnes@confidentstages.com. Para mayor información, visite confidentstages.com


millennials gen y

Generation Gaps in Business: The Abyss of the Millenniums

millennials gen y

Being a business owner, employer or leader in today’s business world requires an awareness of the needs of all the generations in the workforce: the Baby Boomers, Generation X, Y and Z. Whether engaging with staff, clients or stakeholders, understanding the differences in generational values and motivations will lead your business to run more effectively and ultimately improve those bottom-line profits.

Change is inevitable…and it’s happening faster than ever before

Where previous generations were fearful of change and determined to hold onto the status quo, Millennials and the new Generation Z view it as exciting and normal.

Some generations have caused more of a ruckus than others. Today, it’s Millennials (also called Generation Y) that are getting a lot of bad press. Entitled, self-absorbed, and unfocused are typical adjectives swimming in the ocean of negativity that describe our workforce’s majority generation. They cannot survive without their cell phones, have grown up playing video games and expect instant gratification. Many argue that this generation cannot make a decision without consulting everyone they know. Others say they are downright lazy and expect respect just for showing up.

Does all this sound familiar?

It should, because similarly harsh criticisms of each new generation have rung through the rafters since the end of WWII. Think back to the panicked parents when Chubby Checker became popular. Remember the «rebels» created by The Beatles? What about the sacrilegious burning of draft cards? Young upstarts have created chaos with every passing generation, and for that we should be completely grateful.

Each generation brings innovation that shapes our future, and your leadership can make all the difference.

Strategic leadership can tame any circus

confident leadershipAs described in Confident Leadership in 21st Century Business: Bridging the Generation Gaps, taking a leadership role in today’s business world is akin to being a ringleader in a circus. With so many different performers and acts on stage, the ringleader must recognize everyone’s talents and provide them with the tools they need to put on a successful performance.

Likewise, a business leader must recognize the different generations within their team and modify the tools and tactics to work with each of them. A leader’s role is also about uncovering what makes each generation tick, and using that information to direct their abilities.

In business, the good leader is aware that Generation X prefers carefully funneled information, Generation Y feeds on mentorship and praise, and the upcoming Generation Z needs to understand how their tasks fit in with the whole.

We created the qualities of Gen Y

Nevertheless, while some people may see the Millennial generation as entitled and demanding, let us remember, they were raised differently than generations before them.

We awarded them trophies even when they lost, and we lauded them for every activity they undertook. By buying this new generation multitudes of electronics, we taught them to understand the world of quick responses, and have instant information at their fingertips. They took advantage of every opportunity to learn the complex world of computers, and we praised them for their ingenuity in solving problems in a flash.

Communication styles changed, and as Gen Y began to grow into their teens, the world shifted toward a dramatically new direction – with unprecedented changes equal to those of the Industrial Revolution. We provided cell phones so we could keep in touch with them, smartphones with instant Internet access and computers virtually anywhere they went. They took advantage of that technology to learn how to adapt quickly, keep in touch with the world and with each other at every moment.

Gen Z: A newer generation impacting business

Gen Z has never known a world without smartphones, wearables, and a world of Internet-connected devices. They are being raised amid institutional and economic instability, are heavily influenced by depleting resources and climate change, and are globally connected via social media. They have always had information at their fingertips, are masters of technology and analytics, and are going to further change the way the world does business. Not even the Millennials will be able to easily understand this new shift.

Young people push boundaries. It is what each generation before them has done – and it is right to do so. We have taught them to fearlessly try new things. We’ve encouraged them to uncover innovative ways to accomplish their goals. This generation is brilliant. Business leaders will find that leading Gen Z to find their fit in the organization will help harness their knowledge and enthusiasm, ultimately driving results and improving profits.

Yes, it is difficult to manage people who know more than we do – and yes, they do things differently than we did. Although memories of life without cell phones and personal computers surface from time to time, it is hard to imagine conducting business today without them. There are fantastic possibilities still to come, the ideas for which will undoubtedly be created by the younger generations of the workforce.

Mentor them, guide them, studiously avoid micromanaging them, and be grateful for the courage of the generations of change.


Business author and speaker, Rosemarie Barnes, highlights the challenges that leaders may face when dealing with multiple generations in one workplace. Learn more about how the generation gaps in business are affecting company health and profits in her book, Confident Leadership in 21st Century Business: Bridging the Generation Gaps, now available on Amazon (US and Canada). Rosemarie can be booked for presentations via rbarnes@confidentstages.com. For more information, visit confidentstages.com.

Chained computer illustration

Are Your Clients Safe from Hackers?

hackers and cybersecurity

When it comes to cyberattacks, the targets are typically the behemoth companies and organizations you read about in the news. But according to IBM, small and mid-sized businesses are the target of 62 per cent of all cyberattacks – which equals about 4,000 attacks per day. The reason? They are an easy target.

Can your company or clients be under attack?

We hear a new story about cyberattacks almost every day. A business gets hacked — allowing sensitive proprietary and customer data to be accessed and compromised. The list of the world’s biggest data breaches is littered with recognizable names, including Anthem, JP Morgan Chase, and Target.

But don’t think for a second that hackers only target large organizations. In fact, small businesses are often just what hackers are looking for. Why? The main reason is that small businesses often have inadequate online security, and with sensitive data housed in the cloud they become an easier victim.

A quick night’s work for a hacker can mean disaster for your business. According to a report by the U.S. National Cyber Security Alliance, 60 percent of small businesses that suffer a cyberattack are out of business within six months.

Nobody will protect your business except you

Banks and the government haven’t done much to assist small businesses with hackers and data breaches. The recently introduced MAIN STREET Cybersecurity Act in the United States will help small businesses protect their digital assets from cyber threats, but it’s far from a silver bullet. Businesses of all shapes and sizes need to start taking data security seriously — proactively and with full accountability.

Now is the time to put together a solid security plan.

Don’t just go with the first solution you find. Instead, take the time to find the approach that fits your business, customers and industry. There is no one-size-fits-all solution. More importantly, don’t leave data security to just the IT staff. Get everyone involved — including your managers and all levels of employees. Train each of them on protection measures and show them how to stay compliant. For example, teaching employees to avoid opening suspicious email attachments can be a safeguard against malware that could easily creep into your network.

If your workforce is highly mobile, you may want to consider the rules around any bring your own device (BYOD) program you may have in place. Security Magazine explains how a BYOD program, whether formally in place or not, could create unintentional risk within the organization — simply based on the lack of awareness of such programs. The publication states that, “17.7 percent of survey respondents who bring their own devices to work claim that their employer’s IT department has no idea about this behavior, and 28.4 percent of IT departments actively ignore BYOD behavior.”

Once you start protecting your company, you must take the next steps to stay safe.

Obtain cybersecurity insurance, create a strong password strategy for your users, and utilize virtual data rooms (VDR). For in-house IT departments and office managers, it’s important to upgrade your tech as well. Start with this list of five tools and services your small businesses can use to protect against cyberattacks.

Taking cybersecurity to the next level

web security and hackers

Want to dig deeper? Consider employing an ethical hacker — a cybersecurity expert who works within your company to locate weaknesses and vulnerabilities by duplicating the intent and actions of hackers.

Also talk to a company that specializes in cybersecurity protection. Many of these businesses will offer free vulnerability assessments to give you an idea of where your weaknesses may lie. They’ll also explain how they can help you manage those threats. If you don’t currently have an in-house IT team, outsourcing the work could be an efficient option.

As if all that wasn’t enough, here’s one more thing to consider. When crafting a data security policy, make sure you’re actually protecting data privacy by including the following nine elements in your policy, as detailed once again by Security Magazine. It’s crucial to consider your policy from all angles – after all, your data can make or break your business.

1 Ensure Data Security Accountability All IT staff, workforce and management must be aware of their responsibilities.
2 Create Policies that Govern Network Services How to handle remote access, IP addresses, routers and network intrusion detection.
3 Scan for Vulnerabilities Have a routine in place for checking your own networks regularly for hacking vulnerabilities.
4  Manage Patches Implement code to eliminate vulnerabilities that can help to protect against threats.
5  Create System Data Security Policies Rules around company servers, firewalls, databases and antivirus software.
6  Have a Response Plan for Incidents If a security breach occurs, have measures for handling the issue along with evaluation and reporting.
7  Educate Staff on Acceptable Use Employees should understand and sign an acceptable use policy, which includes disciplinary action.
8  Monitoring Compliance Regular audits to ensure staff and management are complying with the data security policy.
9  Account Monitoring and Control Designate someone to monitor and control users, and keep track of active and inactive user accounts.

It seems like a lot, but it can be done. More importantly, it must be done. When it comes to today’s advanced hackers, organizations must be prepared for when — not if — they will have a data breach. Taking small steps now will ensure you’re not facing bigger problems down the road.

soical selling

What are the world’s best sales reps doing right?

soical selling

The world’s top sales pros are uncovering hotter leads, winning bigger deals and earning more revenue than their peers – all because of awesome new sales tactics. So what is their secret? The key is adjusting your playbook the right way — and adding three key sales techniques.

According to Jonathan Lister, Vice President of Sales with LinkedIn Sales Solutions and Country Manager of the Canadian division, social selling has become the new norm – at least, for those top sales pros. And they’re using these techniques to beat their competition.

Lister also revealed the old-school sales tactics you need to swipe left from your playbook immediately while presenting at a “State of Sales” workshop at the LinkedIn Toronto headquarters. His information is based on hard facts, as discovered through LinkedIn’s “Global State of Sales Survey” that researched exactly why top sales reps were performing so well. So there’s no doubt that following this advice could produce major rewards.

Curious what isn’t working? Take a look at part one of our story, then keep reading to learn the three tactics you need to add to your playbook today.

1. Target the full buying committee

Remember those six to eight decision-makers from part one? Those are the exact people you need to target. Thanks to online networking, you now have immediate access to social websites filled with valuable data on all of these people – most notably across the three main networks; LinkedIn, Twitter and Facebook.

Lister explained how your prospects are checking in every day on these networks, learning new skills, and connecting with colleagues. In many cases, they are also raising their hands to ask for help when they have a business issue. “The top sales pros are learning exactly what their prospects are doing online.”

The key is to target the full buying committee on social media by connecting with each of those people individually – first on LinkedIn and Twitter, as these are the more common networks for business relationships. Connect with them on LinkedIn, join the same groups as them, follow them on Twitter, and even add them to one of your Twitter lists, which will show you’re taking a more active interest and value their profile. Get to know what they’re posting and what they value. When you eventually reach out with your ‘ask,’ the information you’ve gathered will better prepare you to customize your pitch.

2. Understand before you ask

It’s critical to learn how certain activities and social news can signal a potential sales opportunity. Understanding this timing is a modern top sales skill.

Lister highlighted five social selling signals, but pointed to one that is the most powerful for top sales pros. “Job changes are one of the most powerful signals of intent,” noting that most job changes are publicly highlighted on networks like LinkedIn. Being aware of these updates and acting on them can get you a step ahead of your competition. “When someone changes jobs, maybe they want to take products they used at their old jobs or find new ones,» he explained. That’s a perfect opportunity to connect and highlight what you can offer.

Similarly, when people make new connections or connect with new groups on LinkedIn, that may signal they’re working on a project or building a team. Content shares and social comments also tell more personal commentary on what someone is interested in. Social comments, in particular, are very powerful indicators of buyer’s intent.

Lister went on to explain how new social selling tools like sales filters and lead bots can be a major benefit when making those connections and learning about sales prospects. “A lead bot will go out and find leads at scale, like the LinkedIn Sales Navigator. It can deliver leads along with a contact’s profile.” And that information can be invaluable since it’s often accurate and up-to-date. Goodbye dirty lead lists.

3. Engage from first contact to final contract

How do you engage with people across multiple accounts and conversations? With so much digital noise, it’s important to cut through that clutter.

First, find prospects from mutually trusted connections. In LinkedIn, that means connecting with people from shared groups and connections. Finding those connections via the Sales Navigator TeamLink feature can also show you how to break the ice with mutually shared connections on your sales team.

Connecting can then include something as simple as a follow request or an introductory message on the platform – called an InMail. Lister explained how every top sales pro cited ‘trust’ as incredibly important in their sales process. “If you can find that at scale, then the open rates can be incredibly high,” speaking about InMail. “But for most sales pros, that’s where it will stop. They’ll make the connection, send a message and get them to open. Then stop. But it’s not good enough. You need them to give you more information and connect meaningfully to create an ongoing relationship and dialogue.”

Top modern sales pros will make those connection paths and then create a “feedback loop.” In Sales Navigator, that can also include using their new PointDrive tool that lets you send a sales package URL that tells you if the prospect opened and consumed any follow-up info. Using the tool allows Lister and his sales teams more insight into their customer’s actions. “Now I have a way to communicate with my prospect, what they’re reading, what’s important to them and how to communication follow up further.”

Whether you have these tools or not, the important part is continuing the conversation with the prospect, answering their questions, solving problems and building a trusting relationship. If you can do that online even before talking in person, you’re well on your way to winning more opportunities and becoming a top sales pro.

social selling

3 sales tactics that no longer work (Plus 3 new ones that do!)

social selling

The state of sales has completely evolved. Old sales strategies no longer work, and any salesperson using traditional tactics likely can’t compete with the modern sales leaders who’ve adopted new methods. Exactly what sales tactics aren’t working anymore, and what should we replace them with?

Jonathan Lister knows a thing or two about social selling. As Vice President of Sales with LinkedIn Sales Solutions and Country Manger of the Canadian division, he recently addressed a workshop audience to explain this shifting trend in sales. Technology has obviously brought forward new ways of engaging with brands, while customers are also interacting differently with their company contacts – resulting in conventional sales teams losing deals.

What can sales teams do to catch up?

As expected, Lister points to the pivotal role of social media for part of the answer. But there is more to the story, as LinkedIn analyzed the results of their “Global State of Sales Survey” and found out exactly why top sales reps were performing so well.

What isn’t working:

These three traditional sales tactics are no longer working. Here’s why you should stop doing them right now to improve your sales playbook.

1. Call high up the ladder

You’ve likely learned that it’s important to talk to a C-suite contact and build a relationship with the top person in a company. Not anymore.

Lister explained that most sales people have to make contact with six to eight decision-makers per deal. Further, 58% decisions are made outside the C-suite.

«If you’re just talking to the C-suite, you’re eliminating at least five people from that sales cycle,» Lister explained. Nowadays, the C-suite isn’t as influential in the sales process. They’re letting their teams take a more active role in the decision-making, and if you’re only focusing on the top dogs, you’re putting too much attention into the wrong relationship building.

2. Lead with great questions

The discovery process, including probing with thoughtful questions, has always been an important sales tactic. Many sales pros have been taught to reach out to a prospect and make a compelling statement to capture their interest.

The problem is that buyers and decision-makers have also been sharpening their skills, including how to recognize sales tactics and then avoid them altogether. So if you’re calling to ask someone to move services or buy a new product, chances are that this savvy prospect will have a rebuttal ready.

«Most buyers think that sales reps aren’t credible anyway,» Lister explains. And simply asking probing questions may only reinforce the idea that sales reps aren’t in touch with the way to connect with prospects.

3. Touch 7 times

Sales pros know that one touch point isn’t enough. That’s where the seven touch point rule stepped in – the theory being that you’ll need at least seven points of contact to close a deal. But that could waste time, resources and shift focus to the wrong part of the sale.

If sales pros are reaching out to their prospects just to get the touch points in, they’re wasting their time. «Reaching out without something meaningful to say is detrimental to the sales cycle,» cautions Lister, who added that a genuine point of contact has been a key component of relationship building with top sales pros.

Unfortunately, the focus for many sales teams has been about hitting the seven touch points — no matter how beneficial those activities were in pushing the sales opportunity to the next level.

What is working:

The good news – the traditional strategy can now be replaced by a set of more modern set of sales tactics.

Read part two to learn the three tactics all top sales pros should be using to connect with new customers.

ultimate entrepreneur mindset

Do You Have the Ultimate Entrepreneur Mindset?

ultimate entrepreneur mindset

How do your entrepreneurial skills, personality, motivation and drive stack up against your peers? Do you have the qualities of the best in the business?

Check out the highlights from our roundup below. Explore what 15 of the hottest entrepreneurs do every day to keep on schedule. Learn the five must-have skills for every top businessperson. Then see if you’ve adopted the entrepreneur mindset to take full control of your business – or if you’re actually thinking like an employee.

Are you starting your day off right?

From Medium

It’s fascinating to see how some of our favorite entrepreneurs, creatives, and thought leaders spend their time every day. What are their morning routines like? What time do they rise in the morning? When are they most productive? How do they relax? …

Some wake up by 4am; others don’t start the day until closer to 11am. Some exercise every single day; others write or meditate. … What’s clear, is that having a routine of some sort matters. Routines help us get into a flow state that unlocks our ability to be happy and effective every day. While there weren’t any across-the-board consistencies, there were some themes:

  • Get a decent amount of sleep
  • Read things that are interesting to you
  • Try to break a sweat daily
  • Spend time with people you love
  • And when you really need to kick into gear, there’s nothing that a good cup of coffee (or an ice plunge) can’t help with 😉

Read on for a glimpse into the daily routines that successful entrepreneurs, creatives, and thought leaders swear by.

Sam Altman, President of Y Combinator

I try to do the things that I think are important, and be ruthless about not doing things that I don’t think are important. This sounds easy in theory, but requires a lot of discipline in practice. I generally have about three big goals and 20 small to-do items for each day.

Steve Schlafman, VC at RRE Ventures

I’m up every morning at 6am. Hot yoga at 6:30am. Breakfast meeting by 8:30am. Back-to-back meetings from 9am–6pm. I might get 30–60 minutes for email in between. Go to a work-related event or dinner with a founder, executive, friend, etc. Spend time with my wife. Read a book from 10:30–11ish. Bed by 11pm. Rinse and repeat.

Joel Gascoigne, Co-founder & CEO of Buffer

These days, I generally have a lot of quick meetings with different people on my team. I’m mainly focused within product/engineering, customer service, hiring, and then on the higher level. My calendar is open to people on the team, and it generally gets quite booked up. I have quick 20-minute sessions to give advice on a specific challenge. I also have 1:1s with several people on the team, so I usually have one of those each day, too. Other than work, I try to exercise several times a week (either strength training at the gym, running, or doing a bodyweight workout at an outdoor gym).

Read full story & all routines…

The 5 skills of the most successful entrepreneurs

From Influencive

In today’s economy, workers cannot depend on having a stable, full-time job with benefits until they retire. Most people will go through times in their career when they work freelance or are considered an independent contractor. Many of us will also begin our own business at some point. In a gig economy, everyone needs to know how to create their own brand. We are all entrepreneurs. …

Most people who go into business have entrepreneurial figures they admire. … Look at what they do and figure out what works for them. You will notice how many entrepreneurs have similar skills.   Once you notice that, you can apply those skills to your own work.

Concentration

Concentration is an important skill for successful entrepreneurs. For our purposes, concentration has two meanings. The first is your ability to focus. Our digital world is full of distractions. We have all experienced the time suck of the internet. Moreover, we are constantly distracted by our phones and keeping in touch with family, friends and co-workers. …

Leadership

Leadership is a vital trait for entrepreneurs. After all, anyone who wants to succeed in building their own brand and/or business should expect to be in a position of authority and to have other people working for them at some point. That means that you need to be able to lead. … Most people need to work at developing leadership skills. Even people who are natural leaders can benefit from working on improving their leadership skills. …

Organization

Organization is a significant trait of successful entrepreneurs. You need to have your ducks in a row if you want to accomplish everything you need to do in a timely enough manner. Organization is another skill that you might have a natural aptitude for, or it might be something you struggle with. Either way, you should view organization as a skill you can learn and improve upon. …

Read the full story for all five skills…

Do you think like an Employee or an Entrepreneur?

From Eric Tippetts

While every human being is different, we do have certain similarities that can set us apart from other groups of people. One of the primary items that group people together are their mindsets.

Entrepreneurs must have mindsets that are quite different than an employee.

Herein lies a common problem I have recognized with new entrepreneurs… They jump into the entrepreneurial world with an employee mindset.

The Key Mindsets of the Entrepreneur:

  • Entrepreneurs focus on the important things: A large percentage of employees are focused on the job they have to do whether it is important or not. The mindset of the entrepreneur requires them to focus on what is the most important, profit making task.
  • Entrepreneurs do not procrastinate: While an employee may put off a task until tomorrow, the entrepreneur is all about doing it NOW! Procrastination is NOT in the entrepreneur dictionary.
  • Entrepreneurs rely on their “gut”: The entrepreneur has to make split-second decisions on a daily basis.
  • Entrepreneurs own their failures: Many employees tend to find excuses for failures, but successful entrepreneurs have learned the success only comes because of multiple failures. The entrepreneur mindset is to own the failure and not put the blame elsewhere.
  • Entrepreneurs set high, but reachable goals: Personally, I believe every person should set goals, but few do. Successful entrepreneurs understand that each day, week, month and year must be a series of high, but reachable goals.

See the full article & all 17 entrepreneur mindsets…


Entrepreneurs also need to have their sales pitch perfected and polished – ready to sell their products and win new customers. Learn how to craft the ultimate 60-second elevator pitch that will capture attention, generate interest and grow your client base.