negotiating business deals

Your Supplier Hikes Your Prices. What’s Your Move?

You open your inbox on a Tuesday morning. There it is: a letter from one of your key suppliers. Effective next month, prices are going up 12%. No negotiation. No warning. Just a gut punch you are expected to absorb.

For most business owners, the instinct is to accept it. The supplier holds leverage. You need the materials. What choice do you have?

More than you think.

This article is a practical response plan for one of the most common and costly surprises in business: the overnight supplier price hike. With U.S. tariffs at their highest effective rate since 1946, the Institute for Supply Management Prices Paid Index hitting 78.3 in March 2026 (its highest since June 2022), and diesel forecast to average $4.80 per gallon for the year, supplier cost increases are hitting nearly every industry at once. 

For businesses in manufacturing, trucking, and distribution, especially those holding fixed-price contracts with their own customers, the math is rough. Your costs go up while your revenue stays level.

But you don’t have to take it lying down. Here’s what to do.

Put Suppliers On The Defense

Before you accept any increase, ask for documentation. Request a written, line-item breakdown showing exactly what inputs drove the change: raw materials, labor, energy, freight, and overhead. Ask for the prior baseline, the current value, and the percentage change in each category.

This request alone changes the conversation. Many price increase notices are test balloons. Suppliers know that most buyers accept without question. When you ask for justification, you signal that you will not.

Once you have the breakdown, verify it. Public indexes let you check the supplier’s claims against real market data:

  • Raw materials: The U.S. Bureau of Labor Statistics Producer Price Index (https://www.bls.gov/ppi/) tracks commodity prices including steel, aluminum, copper, lumber, and resins.
  • Diesel and fuel: The U.S. Energy Information Administration (https://www.eia.gov/petroleum/gasdiesel/) publishes weekly on-highway diesel prices by region.
  • Labor costs: The BLS Employment Cost Index (https://www.bls.gov/eci/) tracks wage and benefit changes by industry and occupation.

If a supplier claims a 15% increase driven by material costs but the relevant PPI shows a 6% move, you have a data-backed case for pushing back.
negotiate supplier price

Negotiate Beyond the Unit Price

Most business owners focus the entire conversation on price per unit. That is a mistake. Experienced procurement professionals negotiate across multiple variables simultaneously. Payment terms, volume commitments, contract length, and delivery scheduling all have value to your supplier.

Consider offering to pay faster. A 2/10 Net 30 arrangement (2% discount for paying within 10 days rather than 30) represents a significant annualized yield for your supplier. That has real value to them. It costs you something, but it may be far less than absorbing the full hike.

Volume commitments work in the same way. If you can credibly offer to consolidate purchasing or extend a contract in exchange for a price hold, many suppliers will take that deal. Predictability has value on their side of the ledger too.

When a cost increase is genuinely legitimate, push for a phased structure rather than accepting it all at once. Accepting 50% of the proposed increase now and deferring the remaining 50% for six months can be a meaningful win. It buys you time to reprice your own contracts, adjust your margins, or qualify a second source.

For any agreement you sign going forward, shoot for indexed escalation clauses rather than supplier discretion. A well-structured clause caps annual increases at a defined percentage, ties adjustments to a named public index (BLS PPI for materials, EIA for diesel, ECI for labor), requires bidirectional movement (when the index falls, your price falls), and gives you at least 60 to 90 days’ written notice before any change takes effect.

Build Your Diversification Defense

A single supplier relationship is a concentration risk. The COVID disruptions of 2020 to 2022, the current tariff environment, and ongoing energy volatility have made that clear. A second qualified supplier for your most critical inputs gives you negotiating leverage and operational resilience at the same time.

The practical approach is a 70/30 allocation. Your primary supplier gets 70% of the volume, keeping your pricing tiers intact. Your secondary supplier gets 30%, enough to stay current on your specifications and able to scale up quickly if needed. Don’t think of it as splitting the relationship; think of it as insuring it.

Qualifying a second supplier takes time. Quality audits, specification reviews, and trial runs rarely complete in fewer than 90 days. The time to start is not after the next hike letter arrives. It is now.

Watch for the next article in this series, which examines the full cost of single-supplier dependency and how to structure a diversification strategy.

Keeping Your Business Running During Negotiations

Here is the practical problem: even a successful negotiation takes time. Your supplier’s new pricing may hit next week. Your bank line of credit increase may take months to process. An SBA loan typically takes 60 to 90 days to fund, even with expedited review.

According to JPMorgan Chase Institute research, the median small business holds roughly 27 days of cash buffer. A sudden 12% increase in input costs can wipe that out fast, especially for businesses with 30 to 90 day payment terms from their own customers. Accelerated burn creates a sense of urgency that threatens your negotiation and your business.

This is exactly where invoice factoring serves a function that traditional financing cannot. Factoring converts your outstanding invoices into immediate working capital, typically within 24 to 72 hours. Approval is based on your customers’ creditworthiness, not your recent margins or credit history, which matters most when a cost shock has temporarily squeezed your financials.

One manufacturing company that Liquid Capital works with faced a similar challenge during the 2009 recession. A major bank pulled their line of credit just as they had landed a large grocery retail contract. Liquid Capital provided $1.2 million through invoice factoring over the course of that contract, allowing the company to pay suppliers, keep production running, and deliver on the order. By 2024, that same company had returned to full bankable status and achieved significant sales growth.

Factoring is not the cheapest form of capital. It is the fastest form that scales with your sales, remains available when banks tighten lending standards, and does not require months of documentation a traditional credit facility demands. When your cost structure shifts overnight, speed has real dollar value.

Slow is Smooth. Smooth is Fast.

When a supplier hike notice lands in your inbox, the response is not a single decision. It is a sequence.

Slow the conversation down. Request documented cost justification and verify the claims against public indexes. Negotiate across payment terms, volume, and contract structure, not just unit price. Phase any legitimate increase and lock index-based guardrails into your next contract. Begin qualifying a secondary supplier. Make sure your working capital can sustain operations through the 30 to 60 days it takes to resolve the situation.

The businesses that absorb cost shocks best are not the ones with the deepest pockets. They are the ones who know they have options and act on them.

To learn more about how invoice factoring can help your business manage cash flow through supply chain disruptions and cost increases, read our guide to understanding invoice factoring contracts.
growth in the energy sector

Leveraging alternative funding to fuel growth in the energy sector

Companies are preparing to seize new opportunities for growth in the energy sector. Are you ready to join them?

growth in the energy sector

For small to mid-sized companies in the energy, oil and gas sector looking for opportunities to take their businesses to the next level, the last couple of years have proven to be anything but easy – but with the industry poised for growth in 2023, putting yourself in a position to be able to take advantage of new projects is paramount.

Although a potential recession is on the minds of many small and medium-sized business owners heading into 2023, growth in the energy sector is set to continue.


Continued recovery after volatility

Helped by factors including tailwinds from the completion of the Trans Mountain Expansion pipeline and the Coastal GasLink natural gas project next year, the Canadian Association of Energy Contractors (CAODC) is projecting a 15% increase in the number of wells drilled in 2023, as well as more than 5,400 direct and indirect jobs created in the sector.

This is a far cry from the situation the sector faced only a couple of years ago.

The first year of the pandemic was volatile for all players in the oil and gas space, with demand for energy products falling – and the industry experiencing historic low oil prices and drilling activity, says the Canadian Association of Energy Contractors (CAODC.)

Following the challenges of 2020, oil and gas extraction industry revenue grew in 2021 thanks to a rebound in economic activity, rising oil and natural gas prices and increased production volume as demand for energy products climbed, says StatsCan.

This year, recovery has continued for the sector as energy prices reached record highs — although oil prices have eased off since the summer peak, they are still well above the levels seen during the early part of the pandemic.

growth in the energy sector Continued recovery after volatility

On the ground, cash flow challenges continue

In spite of improving conditions for many oil and gas companies, small and mid-sized energy firms still face challenges when it comes to cash flow and getting invoices paid on time.

Although many smaller producers are building relationships with large, reputable customers in the oil and gas sector and have agreements in place for their invoices to be paid at net 30 days, payment often gets extended to net 45 or 60 days.

In many cases, customers in the sector are stretching out payment terms even as far as net 90 days, because of the realities of their own cash flow cycles. When combined with small margins, many energy companies find it hard to take advantage of opportunities to grow.


How alternative funding helps energy companies succeed

As Deloitte notes, more than 90% of oil and gas executives are positive about the industry in the coming year. With the chance to take advantage of new business in the sector, having quick, reliable access to working capital is essential. In this economy, however, banks are tightening their lending criteria and re-evaluating lending risk as interest rates rise.

An alternative funding solution like invoice factoring can help ensure you’re in a position to hire new employees, meet payroll and confidently say yes to taking on new projects.

Whether you are in exploration, extraction, refining or another part of the upstream or midstream oil and gas industry, an alternative lending partner with the expertise in helping companies in this sector grow is not only a source of working capital – but will see the potential in your business, go deeper into your story and be a valuable source of advice as you navigate your next steps.

How alternative funding helps energy companies succeed

With large, credit worthy customers in the sector, small and mid-sized oil and gas companies are perfectly positioned to take advantage of invoice factoring. This flexible solution will help accelerate your cash cycle, quickly replacing your near-current assets — or invoices — with cash. 

With an invoice factoring solution, your business will receive up to 85% of the value of your invoices and the factor collects payment from your customers on your behalf. The process can also be customized to meet your needs, so you won’t be locked into a long-term contract.

Asset-based lending is another flexible funding option that allows you to secure a line of credit against all your valuable assets, including accounts receivable, inventory, equipment and real estate. With borrowing amounts typically calculated weekly, the ability to borrow can increase more quickly for companies in a strong growth cycle.

Looking to the future

With demand in the energy sector set to continue in 2023, forward-thinking energy companies are looking to agile, flexible funding solutions to ensure they’re positioned to take advantage of opportunities to build relationships and grow their market share.


Are you or your client looking to access flexible funding for your energy company? Contact a Liquid Capital Funding Expert today to learn how our alternative funding solutions can help you be ready for anything.


growth in the manufacturing industry

Remain agile and lay the groundwork for growth in the manufacturing industry

To experience growth in the manufacturing industry, companies need to be ready to pivot in the face of changing conditions.

growth in the manufacturing industry

While demand has recently been steady for companies in some sectors, for others it has eased off. For instance, this year in the manufacturing industry, persistent industry and economic roadblocks are making it hard for manufacturers to stay agile, meet their obligations and take advantage of opportunities to grow.

So what is the best way forward for manufacturers, no matter what scenario they find themselves in? Keep reading to find out more about the factors affecting growth in the manufacturing industry and why having the working capital to stay flexible is critical to success.


Unpredictability is the new norm for manufacturers

For most in the industry, conditions have been in a constant state of flux over the last three years, starting with the COVID-19 pandemic, where restrictions affected more than 85% of Canadian manufacturers in 2020.

The sector faced major supply chain issues between the onset of the pandemic and summer 2022. In Canada, the total number of manufacturers dealing with raw materials shortages nearly tripled during that time. And a July 2022 Deloitte survey of more than 200 U.S.-based manufacturing executives found that shipping delays and part shortages had the biggest impact on manufacturers’ supply chains in the previous 12 to 18 months.

Respondents also noted that their top operational concern is the rise in shipping costs, which Deloitte says rose by more than 77% from January 2021 to August 2022, due to rising fuel prices, labour costs and logistics challenges.


Manufacturers may have also experienced suppliers reneging on contract pricing, increasing their costs at short notice in response to rapidly shifting global conditions, such as COVID-19 restrictions and the war in Ukraine.


While sales came back – growing nearly 28% between January 2020 and June 2022 — challenges continue. Although the Bank of Canada notes that inflationary pressures from supply bottlenecks are easing, economic growth is expected to slow next year – to 1% in Canada and 0.2% in the United States.

Faced with their own economic hurdles, your customers may be paying their invoices at net 45, 60 or even 90 days – creating a longer payment cycle that hinders your ability to meet your payment obligations or even to take on more contracts.
In tough economic conditions, ensuring your manufacturing business can continue to thrive really means having enough working capital on hand to pay employees and meet day-to-day obligations, as well as purchase inputs and take advantage of any opportunities to grow your market share.

But as many traditional banks are tightening lending criteria, this may mean looking to a more flexible funding solution.

helping manufacturers through a volatile market

Alternative funding — helping manufacturers through a volatile market

Finding a funding partner that considers the creditworthiness of your customers — not the immediate challenges facing the industry — may be the ideal solution for manufacturing companies looking to meet day to day obligations in this environment, and those hoping to take advantage of strategic opportunities to grow.

Even if your manufacturing business doesn’t align with traditional lending guidelines, asset-based lending (ABL) or invoice factoring , can offer you alternative financing that’s both fast and flexible.

For companies with a strong credit rating and verifiable financial reporting (such as receivable and payable summaries), ABL has the ability to secure loans against your accounts receivable, inventory, equipment and real estate.

Similarly, invoice factoring can also help manufacturers accelerate their cash cycle, quickly replacing near-current assets — or invoices — with cash.

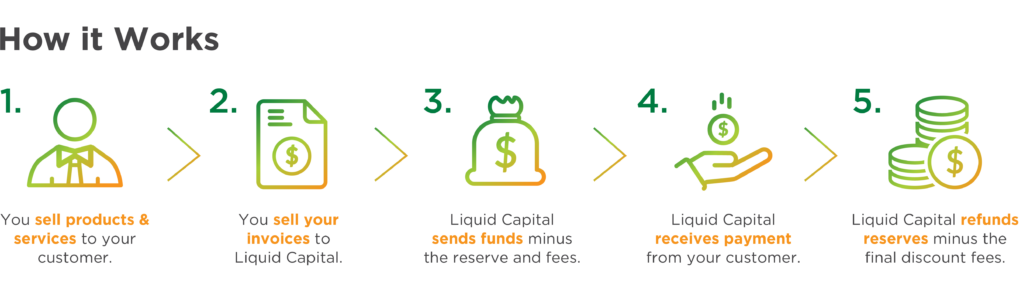
With factoring, Liquid Capital purchases your outstanding invoices, advances your business up to 85% of the value of your invoices and collects payment from your customers — which allows your company to avoid costly interruptions to your manufacturing cycle. You receive the working capital you need to pay employees, replenish inventory or components to make further sales — and take advantage of opportunities to grow your business.

Factoring-How-It-Works

Perhaps just as importantly for manufacturers in this market, by working with an alternative lender, you’re forming an invaluable partnership with an experienced advisor who has deep knowledge of your industry, will look past current challenges to see the potential in your business and will work alongside you to find the right funding solution.

Looking beyond traditional criteria

Take E-Systems Corp. for example – an electronic contract manufacturer providing services and products to major U.S. defense contractors, health care device manufacturers, and the entertainment and consumer electronics industries. Although the company was on a high growth trajectory, it still didn’t meet the rigid, technical criteria for traditional bank financing.

Invoice factoring represented the ideal way for E-Systems Corp. to free up money tied up in accounts receivable, to fund its rapid growth.

While E-Systems Corp. had a huge backlog of booked orders — almost $1 million worth — it lacked the funds to buy the supplies it needed to manufacture orders. To further complicate things, as the company formed through the acquisition of another firm, it was considered a new entity and didn’t qualify for traditional bank financing. The owners also were not willing to give up equity to attract additional capital.

However, its strong portfolio of credit-worthy invoices made the company a prime candidate for invoice factoring. Through factoring, the company was not only able to receive between $85,000 and $125,000 of funding each month, but also the critical advice and partnership that Liquid Capital provides that extends far beyond factoring.


“Whenever a company is growing, it will experience cash flow anomalies. Factoring helps us reduce the time delta between paying our suppliers and getting paid by our customers. It provides us with the up-front cash we need to finance our growth.” — Ron Finlayson, Chief Executive Officer & Chairman, E-Systems Corp.


For another manufacturing company seeking a more flexible approach to financing, Liquid Capital’s approach to invoice factoring also proved to be the right move. Ridgeline Manufacturing, manufacturers of aluminum recreational products primarily for the summer, had limited off-season cash flow and challenges accessing traditional financing as their building and tangible assets were only worth 40% of their original price tags.

Ridgeline Manufacturing

While Ridgeline pursued invoice factoring with other providers, co-owner Nick Newman was not in favour of the short-term approach or lack of flexibility within most factoring contracts, including the need to pay interest on lines of credit even if he wasn’t using the funds.

After meeting with Liquid Capital, Nick liked the idea that there were no minimums and no penalties for factoring one day and not the next. He also appreciated that Liquid Capital didn’t charge interest on money already collected.


“Sure, factoring is higher interest, but we build it into the cost of our product and it’s seasonal. So if I pay more than I would with a bank, but can factor for just a few months a year, that’s a big bonus.” — Nick Newman, co-owner, Ridgeline Manufacturing


Staying flexible in this economy to achieve success

With conditions changing rapidly in the industry and the broader economy, a manufacturer’s ability to respond quickly to meet challenges or opportunities is crucial to success. Agile manufacturers are leveraging alternative funding to get quick access to the working capital they need, bypassing the bank bottlenecks that are even more pronounced in this economy, so they can keep things moving.


Are you or your client looking to access flexible funding for manufacturing? Contact a Liquid Capital Funding Expert today to learn how our alternative funding solutions can help you be ready for anything.


long-term organizational success

Fostering innovation for long-term organizational success

Leaders need to foster and embrace innovation in their companies to unlock long-term organizational success. 

long-term organizational success


For businesses in most sectors, continuing to adapt, focus on and embrace innovation is critical when it comes to standing out from competitors and overcoming oversaturated markets — ultimately cementing your long-term success.

In fact, according to one study eight out of 10 digitally maturing companies say innovation is a strength of their organization, as they report constantly driving toward digital improvement and investing more in innovation than less mature organizations.

But as Deloitte’s 2021 Innovation Study found, for some companies, innovation has become both a business-critical concept and a buzzword that means nothing at all.

To avoid simply paying lip service to the broad concept of ‘innovation,’ which can result in missed opportunities and put you at risk of falling behind the curve, leaders need to nurture an environment where productive, valuable ideas can genuinely flourish.

For many, the key to success means zeroing in on the ideas and processes that offer the greatest value and exploring how best to encourage creativity across your entire team.

Here’s how you can shift towards a management approach that fosters innovation:


Move away from hierarchical management structures

Although most of a company’s business knowledge required for innovation comes from non-management employees, says the Harvard Business Review (HBR) — many consider innovation outside of their remit. Others may be discouraged from participating in the process by cultural norms or organizational barriers like authority bias. As a result, allowing bottom-up innovation to thrive requires a move towards cultural flatness.

As McKinsey explains, flattening and unstructuring your company can unlock a great deal of long-term value. When you minimize management layers and ‘decentralize’ the innovation process, your company can gain  greater speed and agility to move at the pace of change.

As an example, Google takes a decentralized approach to innovation, where different product groups are encouraged to work independently of one another.

This approach will help you empower the front line of your organization to make decisions and enable those closest to customers, clients and products to have a voice and collaborate – allowing for more rapid innovation and effective decision-making.

long-term organizational success

Focus on offering value to the human experience via technological advances

Making moves to integrate more artificial intelligence (AI) into the workplace can help employees find better, more efficient ways of doing certain tasks, freeing them up to think more creatively.

As HBR notes, automating processes by using smart technology can make workplaces “more fulfilling and less exhausting” for employees. However, it’s important to note that employees should still be responsible  for tasks that require empathy and intuition.

Essentially, smart tech can take over the more mundane tasks, leading to a more manageable employee workload and reduced stress, allowing people to focus on other activities like problem solving and intuitive decision making.

For example, time-saving software, such as online collaboration or project management tools, can take basic processes out of employee hands and add valuable time to their schedules, so they can take on more innovative tasks.

innovation system

Develop a system to identify where innovations may arise

As an absolute necessity to the long-term growth and success of your business, innovation and potential innovation needs a metric. Just like sales and marketing initiatives, you need to know where you should be directing your attention – and your funding.

As CEO World magazine explains, while it is a creative process, innovation is also about discipline, so it can be measured – as long as your company is clear on what you mean by innovation. For example, is innovation something new and disruptive in your industry, or simply an improvement to your existing products or services?

Implementing a system to take stock of where innovation is happening in your business is not always easy, according to the Mack Institute for Innovation Management at Wharton. For example, while some companies look at financial metrics like percentage of sales from new products or revenue growth, it’s hard to link this data exclusively to certain innovations or processes.

Instead, consider process effectiveness metrics when measuring innovation, says the Mack Institute, such as the percent of projects that are major improvements, number of new products launched, average time to market, cost/investment and patenting activity.


If your company is ready to unlock the tremendous value of fostering innovation, you need to have a solid plan with concrete steps to analyze and support your company’s journey. That includes having the working capital you need to achieve your goals.


Need a reboot to your cash flow strategy to support your growth plans? Contact a Liquid Capital Funding Expert today to learn how our alternative funding solutions can help you be ready for anything.


now-is-time-to-find-the-right-funding-partner

A recession is looming – now is time to find the right funding partner

As business owners face a recession, the time has come to find the right funding partner to support them as they face new challenges and opportunities.

now-is-time-to-find-the-right-funding-partner

Just as companies are finally moving past the challenges the last few years brought, more economic woes are waiting in the wings. As interest rates rise in both the U.S. and Canada – with promises of further increases — and inflationary pressures persist, the threat of recession is now on the minds of almost every business leader and entrepreneur.

As one recent survey noted, nine out of 10 U.S. small business owners say economic trends such as inflation, supply chain issues and workforce challenges are having a negative effect on their businesses. Some 93% of U.S. businesses are also worried about the economy experiencing a recession in the next year.

Their worries may be well founded. According to the World Bank, the trend of central banks around the world raising interest rates simultaneously in response to inflation is likely to continue well into 2023, edging the world towards a recession.

For most sectors, rising rates, inflationary pressures and a looming recession are linked to a number of challenges. This includes pricing and contract-related concerns, higher borrowing and input costs along with supply chain slowdowns and staffing shortages. 

Businesses in industries heavily affected by fluctuations in cost, supply chain pressures and changes in business and consumer confidence are particularly vulnerable. According to data from the Canadian Association of Insolvency and Restructuring Professionals, this is most prevalent in the construction, transportation and warehousing sectors, with insolvencies increasing this year for many companies.

For many small and medium-sized companies, successfully navigating this part of the economic cycle will mean having the agility and availability of capital to pay employees and meet demand from customers.

With rising costs affecting inputs, even those experiencing high growth will need access to funding quickly to take advantage of opportunities in their market.

Recession-and-traditional-funding-challenges-go-hand-in-hand

Recession and traditional funding challenges go hand-in-hand

Unfortunately, just when cash flow is paramount, gaining access to it via traditional means has become more challenging as rising rates are causing banks to re-evaluate their lending risk.

In the second quarter of 2022, U.S. bank lenders began to tighten lending standards for commercial and industrial (C&I) loans to businesses of all sizes, according to the Federal Reserve’s Senior Loan Officer Opinion Survey. This tightening is expected to continue for the rest of 2022, as businesses are faced with an expected deterioration in debt-servicing capacity due to inflation, an expected deterioration in collateral values and an expected increase in the exposure to interest rate risk.

Finding an entrepreneurial partner

For many companies, the ability to thrive when a recession hits will mean having quick access to funding via a lender that looks beyond the data and takes the time to really understand your business.

In this climate, leveraging the close-knit relationship that develops between an alternative lender and small business will allow you to weather the cash flow challenges that a recession can bring. You’ll be prepared for working capital interruptions and – perhaps even more importantly – they’ll give you the tools required to take advantage of opportunities when they strike.

Looking at business through an entrepreneurial lens, established and partnership-oriented invoice factoring companies take a hands-on approach to client relationships. They take the time to dive deep into the data and seek to understand a company’s purpose and goals. 

They empathize with the financial and emotional impacts facing businesses during times like this, and are ready to discuss potential problems and solutions and aim to collaborate and grow with their clients.

Alternative-lenders-are-nimble-and-respond-quickly-to-challenges

Ultimately, with the unpredictability of the changes that can emerge during a recession, it is important that a lender also has the flexibility to pivot and react, provide predictability and transparency, and give business owners the tools they need to proceed with confidence.

Alternative lenders are nimble and respond quickly to challenges

At Liquid Capital, our clients are just a call or click away from a funding decision, following the initial underwriting process. This can be tremendously helpful in an economic environment where opportunities and challenges arise quickly, and often, unexpected.

It’s common for financial institutions to be slower at approving requests for funding. They can potentially be required to wait for a company’s fiscal year-end or the results of an audit before distributing funds. Operating on a quarter-by-quarter basis, traditional banks also often have little incentive to issue loans with a high cost of administration, especially in the current environment, and consider companies with exponential growth to be higher risk.


One small business recently had the opportunity to scale significantly after landing a large contract to sell their product with a major U.S. retailer. However, the fact that the contract would represent 85 percent of their sales was considered by a bank lender to be too concentrated.

The company instead pursued an invoice factoring solution. Liquid Capital built a relationship with the large retailer’s accounts payable team and was able to notify and verify the receivables. This allowed the client to access the financing to buy the inputs to meet the sales demand – eliminating the need for the company to consider other options, such as prematurely selling equity in the business.


At the centre of the alternative business lending philosophy is a simple concept: a company that is not traditionally bankable can still be a high-growth business.

Finding a funding partner who takes the time to understand your company is one way to guard against the impact of a recession. Keep reading for more tips on how you can prepare your business for the new economic reality.


Up next: Navigating unexpected supplier price increases  


Alternative-business-funders-are-fueling-entrepreneurism

Alternative business funders are fueling entrepreneurism — and the economy

During unstable market conditions, alternative lenders are here to keep fueling entrepreneurism.

Alternative-business-funders-are-fueling-entrepreneurism

Most entrepreneurs have a certain level of risk tolerance baked into their DNA. It takes courage to have a dream, come up with a solid business plan, and make the leap towards realizing it, but sometimes you need a bit of outside help…particularly when finances get a little tight. 

And let’s face it — with recent changes in the economy — rising interest rates, contraction, supply-chain issues — it’s not getting any easier to sleep well at night.

That’s where alternative business funders come in. 

They can help you accelerate cash flow quickly — often faster than you would with traditional banks. This is particularly helpful when you need to jump on business opportunities as they happen. 

Plus, the application process is often easier, with fewer hoops to jump through compared to banks. This makes alternative working capital providers an attractive option when you’re dealing with a lack of cash flow due to late payments from your customers.

Banks are great – when you meet their criteria

When you try to access financing through a bank, you’ll typically need to meet a lot of eligibility requirements first: things like showing a substantial annual revenue, having a high credit score, exhibiting consistent cash flow, and proving you hold a strong debt-to-income ratio. After all, the bank wants to minimize their risk of loss. 

These requirements are not a problem for larger, more established companies. But a start-up or smaller business often won’t meet these criteria. This—maybe unfortunately for you—means many prospective small business borrowers get turned away by the big banks at a time when they’re counting on a cash infusion to keep them going. Scary times for an entrepreneur.

Agile and ready

There is another option. Alternative working capital providers have grown in popularity, mostly due to their accessibility, flexibility, and speed (compared to old-school, bricks-and-mortar banks). This makes alternative funders like Liquid Capital a great fit for entrepreneurs. 

In fact, statistics show that as a small business owner, you’re more likely to get approved for a loan through an alternative funder than a traditional bank or credit union.

How does alternative funding work?

Instead of complicated applications and strict eligibility requirements, alternative funding companies make it easier for entrepreneurs to get the cash flow you need, when you really need it, thanks to:

  • Lower credit score requirements: Alternative funders will often approve loans for new or small businesses that may not have the kind of credit score traditional banks require.
  • Faster approval: Banks can take weeks or longer to approve a loan, but alternative funders can often get the funds you need into your hands in as little as a week.
  • Easier qualification: Trying to get a loan with traditional financial institutions is often a complicated lending process which doesn’t favor entrepreneurs and small businesses.

Partnership: A good funding partner will take the time to truly understand your business challenges, goals and opportunities, propose a strategy that maximizes value for your business, and will remain an accessible and trusted partner throughout the process.

Creative financing solutions made for entrepreneurs

Alternative funders like Liquid Capital specialize in thinking the way entrepreneurs think. We know you need to be nimble with your financing, and often don’t have a long history of past performance to show to qualify for the funds you need. So we find other ways to get you the financing you need, such as Invoice Factoring and Asset-Based Lending.

Creative-financing-solutions-made-for-entrepreneurs

Invoice factoring: your go-to working capital resource

Invoice factoring is one of the ways you can quickly inject your small business with cash. It’s simple: you sell your credit-worthy invoices to a funder like Liquid Capital, and you’ll get paid out a percentage of their value right away (usually 80% or more). It’s an advance on payments – not a loan. In essence, you’re transforming money you’re owed into money you can use to help float your business.

This kind of alternative financing is perfect for entrepreneurs, because it’s much easier to qualify for since your invoices act as security for the funding. If outstanding invoices are affecting your cash flow, invoice factoring could be the right solution for you.

Factoring-How-It-Works

Get ahead of the game with alternative lending

In today’s world, it’s easy for entrepreneurs to fall prey to the whims of an ever-changing economy. Having the right network of investors in your corner can make the need for unexpected financing a lot less stressful. Taking a creative approach to funding with an established and collaborative alternative funding provider can be the right move to help ensure your business dreams stay aloft. 


Are you or your client looking to accelerate cash flow? Contact us today to learn more about how invoice factoring can help.


Invoice factoring mythbusters

Invoice Factoring Mythbusters: Part 1

Alternative funding options are often overlooked sources of financing, but they can help businesses grow exponentially. Here’s what you need to know about invoice factoring.

Invoice factoring mythbusters

Invoice factoring is probably the most unique — and misunderstood — of financing options available to businesses. It’s not a loan or a line of credit, and it’s one of the oldest funding solutions around. 

Invoice factoring (also known as factoring or accounts receivable factoring) is an efficient way for companies to accelerate their cash flow. Most businesses have regular expenses they need to pay while working capital is tied up in outstanding invoices. When you leverage invoice factoring services, you can convert those invoices into immediate cash, rather than having to wait several months to receive the money. 

So what’s true and what’s not?

We examine 5 common myths about invoice factoring and the truth behind this unique financing option.

1. The paperwork required can be time-consuming and overwhelming

This can be the case for some business loans, but invoice factoring is quite straightforward and easy to set up. Also, you could choose to only factor certain clients’ invoices, to make the process even more streamlined (such as only factoring your top 10 customers’ invoices).


“With financing, it’s important to shop around, do your research and make sure you understand the product. The solution must be transparent and deliver on its promise, and we honestly didn’t see anything that was as easy to understand as what Liquid Capital offered. There’s so much confusing—sometimes misleading—information out there; when you come across a company that’s telling the truth with no hidden items, it’s such a big help. It really gave us a comfort level we didn’t have with other providers.”Ken Fincher, President, Defense Product Services Group USA Inc.


2. Start-ups don’t qualify for invoice factoring

Many start-ups struggle to qualify for regular financing options, such as loans or lines of credit, and so might think they wouldn’t qualify for invoice factoring. However, because this financing option is an advance on outstanding invoices, rather than a loan, many start-ups can indeed qualify for it.

These are the qualifying factors that we focus on:

  • You sell products or services to other businesses, not consumers.
  • Your customers have good credit and consistently pay on time.
  • Your invoices have payment terms (such as net 30, 60 or 90 days).
  • Invoices are within specified credit terms and credit limits.

3. My customers might think my business is in financial trouble

While factoring can be helpful for companies with cash flow issues, it’s also a useful financial strategy used by many large and growing companies that want speedier cash flow so they can expand faster. 

Many B2B companies are now used to paying their invoices through a factoring company, especially in certain industries. They won’t think twice about it and certainly won’t assume you’re in financial trouble.

customer success

4. Invoice factoring is only for large companies

Smaller companies and start-ups may be under the misconception that factoring is only for big businesses with huge numbers of invoices, but this is simply not the case. In fact, Liquid Capital deals predominantly with small and medium-sized B2B companies. 

5. The advanced money can only be used for specific expenses

This can often be the case for term loans: banks will only lend for specific reasons, such as for buying equipment or machinery. Invoice factoring is not a loan, however, so it doesn’t come with restrictions on how the money can be used. You can use the money to make payroll, pay monthly expenses or finance expansion — anything you choose, in fact.

Selecting the right funding partner

When using alternative financing options such as invoice factoring, it’s  important that you select the right funding partner for your business (or your client’s business).

While there are many invoice factoring companies, not all of them are cut from the same cloth. It’s important that you and your funding partner share common values and a desire to work towards the same goal – accelerating your cash flow and keeping your business growing.

Contact us to find out more about how you can improve your cash flow by turning your invoices into immediate cash, with Liquid Capital’s invoice factoring.


values based partnership

The importance of shared values in referral partnerships

When it comes to an ecosystem of funding referral partnerships, what determines whether a relationship is likely to last or be successful? Hint: it all comes down to sharing your values.

values based partnership

Whether you’re a business development officer, finance professional, accountant or agent, the seeds you plant will determine what comes to fruition down the way.

While speed and responsiveness are key to relationship building, they will always be trumped by trust—and trust is determined by offering reliable counsel. That means putting people first and seeing relationships as the ultimate drivers of business growth.

Business professionals play an important role in driving economic growth for the businesses they help. Indeed, 92 per cent of respondents in a Nielsen report say they trust recommendations from people in their professional network more than any other source. And 88 per cent of B2B decision-makers rely on word-of-mouth (both online and offline) for “information and advice,” according to Capterra.

Building a relationship-based business

Perhaps a client has reached out, but you’re unable to help with their specific business challenge. Maybe they need help outside your area of expertise. Or maybe they don’t yet meet the minimum requirements to access traditional funding options. However, you still want to help your client and maintain a good relationship.

If you help businesses deal with cash flow challenges, you could be working with a variety of funding partners—and you may be looking for (or already using) a referral partner that specializes in alternative business funding. But without a values alignment, you may not be in the same position to service your clients with the advice they need.

Building a relationship based business

Working with a referral partner who specializes in alternative business funding can help you grow your business, while helping your clients. But you want to make sure that any partner you work with will act as an extension of your brand—and maintain your reputation as a trusted advisor.\


Why do you need a referral partner?

There are a lot of reasons to consider this type of strategic partnership. First off, you’re putting your client first and helping them meet their needs, even if you can’t help them directly. Creating a great experience for your clients will increase the likelihood they’ll return to you in future and recommend you to their network.

And, if you build a strong relationship with your referral partner, they’ll also be more likely to send their clients your way. And you may even receive a referral bonus if your client’s financing request is approved by your referral partner.

But recommending a client (or potential client) to another business partner can be daunting. After all, you don’t want to risk your reputation. Before entering into a partnership, take the time to research your potential referral partner. You’ll want to find out what kind of funding solutions they offer, their terms and rates, and how long they’ve been in business.

Questions to ask:

It’s also important to ask questions to help ascertain whether they’ll be a good fit for your business—which goes beyond their stated capability to fund deals.

  • Are your goals, values, missions and business needs aligned?
  • Are they a thought leader in their field?
  • In which ways are they at the forefront of their industry?
  • Have they demonstrated a willingness to go deeper to find a solution with other clients?
  • Most importantly, will they uphold your reputation if you send them clients?

Taking a people-first approach

Taking a people-first approach

Taking a people-first approach turns a transactional relationship—one that focuses on providing a service or fulfilling an order—into a dimensional partnership. That means focusing on building a relationship, not completing a transaction, even if it means referring business elsewhere.

For example, when Claudia Serna started her trucking business in San Marcos, Texas, she had just one truck. Over the years, she expanded her fleet and built up a highly successful business. But, like many other business owners, she struggled with delays between receiving payments from her customers and paying her subcontractors.

So she turned to her business advisor at the Greater Austin Hispanic Chamber of Commerce, who in turn suggested she seek assistance from his connection at Liquid Capital. After getting to know Claudia’s business needs and challenges, the Principal at Liquid Capital in Austin helped her set up invoice factoring so she could immediately pay her subcontractors—and significantly improve her cash flow, growing the company by 20 per cent.


Read the full story here: Serna’s Trucking: Driving results within the construction industry


This was good for business, but also built trust with her advisor at the Chamber of Commerce. Serna’s Trucking—which sees consistent year-over-year growth—is now a strong contributor to the local economy, and Claudia uses her success to make donations and give back to the community, including assisting teen sports programs at local schools.

Relationships are everything

Working with a referral partner who shares your values will help your clients in a way that will deepen your relationships and expand opportunities for your business. Finding the right strategic partnerships not only helps to build your reputation, but can also take your business to the next level in unexpected ways.


Liquid Capital has been funding businesses for more than 20 years, deploying over $3 billion in working capital in more than 35 industries. Find out more about the Liquid Capital Referral Program here.

supplier contracts

Navigating unexpected supplier price increases

How can businesses remain competitive in today’s market when faced with navigating unexpected supplier price increases?

supplier contracts

Small and medium-sized businesses have gone through tough times over the last few years. With unfavourable market conditions pushing businesses to make hard decisions, many companies are facing new and increasing challenges.

Decades-high inflation has made pricing and contracts more difficult to navigate, and, along with labour shortages and continuing supply-chain delays, some businesses have been struggling to keep moving forward. 

This is particularly the case for B2B businesses that operate on small margins and offer fixed-price contracts, such as manufacturing or trucking and transportation companies. 


Companies in manufacturing, transportation and energy have seen instances where suppliers have increased costs by as much as 20%, even though they had a contract in place at a lower price. 


So how can business owners continue to deliver at the fixed-price contract rate? Keep reading as we examine this growing problem and how small and medium-sized business owners can overcome it. 

Contract reneging is a wide-reaching issue

In recent months, we’ve heard of numerous instances where North American-based companies have had suppliers increase costs at short notice. This is causing strains to their cash flow and putting their client relationships at risk. 

Manufacturing, transportation and energy have seen an increase in suppliers reneging on contract pricing. Often in these sectors, purchase agreements are locked in for years or are structured in such a way that they can’t simply pass along the increased costs to their customers. 

Supplier increases

If a business depends on one or two large accounts (such as a company that is selling products to a grocery chain or a transport company who provides exclusive shipping rights to a single customer) the last thing they want to do is damage or lose a contract. 

So what is the driving force behind this phenomenon and what can business owners do to overcome the cash flow challenges it presents?

Dramatically shifting market conditions to blame

The fall-out from COVID-19 lockdowns and ongoing supply issues are partly to blame for the increase in supply prices. Continuing lockdowns in China (which is the world’s leading manufacturer, with almost 30% of the world’s output) have had serious impacts on the supply of goods and materials. 

The Russian invasion of Ukraine has played a large part in the increase in global prices for oil, which in turn has raised the costs of transportation and the overall cost of a wide variety of supplies. The war has also caused an increase in energy and food costs, bringing a knock-on effect to the price of many other materials. 

The cost of moving goods around the world has also increased considerably. In some places the price of transporting a container almost quadrupled within a year. Labour shortages and wage increases have also had an impact on the cost of most goods and materials. 

These pressures have brought about unavoidable chain reactions: businesses’ costs have spiralled and so the goods they provide have also had to jump in price. 

For the foreseeable future, these pressures are likely to remain for many businesses. Between 75% and 84% of businesses expect to continue seeing increased supply costs, supply shortages and delivery delays.


Manufacturers are facing almost $1 billion in increased costs, with 80% admitting that they have had to considerably raise their prices and delay deliveries of orders.


It looks likely, therefore, that suppliers reneging on contracts is likely to be a reality for many businesses, for some time to come.

How businesses are reacting to increased costs

To stay afloat, many small and medium-sized businesses know that they have to continue delivering on their contracts, regardless of higher costs they themselves may face. Increasingly, therefore, companies are reconsidering the viability of offering fixed-price contracts. 
No business with small profit margins can continue to swallow price increases that can’t be passed on to the customer. More and more companies are providing estimates but no fixed price, so they have leeway to account for potential fluctuations in the cost of materials. 

This is fine for the future, but how can companies manage increased costs which they can’t pass on to their customers, right now?

Financial ways to bridge the gap

Many companies will need extra financing to help bridge the gap between what they’re paying for materials and what they can charge their clients. They can, of course, apply for a loan or line of credit with their bank. However, the big banks are typically more risk-averse than other lenders, and less likely to approve loans to small businesses that are experiencing cash flow issues.  
This is where alternative lenders could come into play. One option is asset-based lending, which provides businesses with a line of credit based on the company’s assets, and repayments which are made on a monthly basis.

bridging the cash flow gap

There is also an option for businesses that need improved cash flow without taking on extra debt. Invoice factoring involves selling invoices for cash, meaning companies can get paid up-front, without having to wait 30, 60 or even 90 days. This can help businesses to deliver on their contract obligations without having to pay debt interest.  

When traditional funding options aren’t available, many companies have benefited from alternative financing options to help them overcome the cash flow challenges posed by the current market conditions. The key is to find a partner who understands the company’s specific needs and is able to provide a funding solution that is in the best interest of the business’s long-term growth.


As one of North America’s leading alternative business funding providers, Liquid Capital delivers agile working capital to small and medium-sized businesses to help accelerate growth. To learn more about our alternative lending options, contact your Liquid Capital Principal today.

alternative business funding strategies

Cash Flow Survivor: Alternative business funding strategies to outwit, outplay & outlast your competitors

3 alternative business funding strategies to help you avoid cash flow exile.

alternative business funding strategies

With 42 seasons under its belt, Survivor has lasted the test of time and remains one of the longest-running reality TV game shows. To win the game, you must not only be strategic and form alliances, but you also need to have sheer determination to overcome the challenges contestants are faced with. 

And when it comes to battling it out in business, finding the craftiest ways of improving your bottom line can often feel like you’re competing for an immunity idol to send  the competition packing. 

Often the biggest obstacle standing between a business owner and success is working capital, and having sufficient cash flow to support your goals. Luckily alternative funding solutions can be the immunity idol that growing companies have been searching for.

Here are three ways to outwit, outplay, and outlast your competitors to the finish line of the fiscal year.

1. Outwit your bank loan challenges

alternative business funding strategies - outwit bank loan


When you need funds, one of the first places you likely turn to is your bank. But banks can have strict criteria and getting that loan can become an instant roadblock. Unfortunately, it’s no surprise that businesses can struggle when trying to access credit and a lack of cash could put you on the chopping block.

To outsmart the traditional loan criteria, form an alliance with an alternative funding partner who can offer you solutions such as invoice factoring — allowing you to sell unpaid invoices to access cash faster. You get paid upfront and can continue operating as usual, even if your credit rating isn’t the strongest. The important part is to form that alliance with an alternative funding partner that has a proven track record and is willing to work with you to advance your business goals.

cash cycle guide

2. Outplay the risk

outplay the risk

Being marooned with no lifeline is a horrible feeling, so it’s important to have a support team to help avoid any risk in the business that can leave you stranded. Whether it be the risk of not getting paid on time (or at all), being subject to fraud, cybersecurity risks, or not getting cash in time to pay your suppliers or staff, you’ll want to mitigate the issues.

To start, ensure that your alternative funding partner has the experience to back up their claims. They should have their own team dedicated to assessing risky funding opportunities, and they should understand your specific cash flow challenges so  they can help keep your torch lit. And since 76% of businesses are concerned about cybersecurity risks, it’s important to work with partners who are equally aware of online risks and take data privacy and security seriously.


Related Read: 5 ways factoring can clear your cash flow hurdles


3. Outlast without giving up equity

Outlast without giving up equity

When you work so hard at growing your business, would you give up equity in the company to gain financing? Many business owners do this, turning to venture capital firms, angel investors, crowdfunding, or even friends and family to increase their working capital. But according to the University of Cambridge, 67% of companies would still rather follow a debt financing model (such as PO financing) than give up a portion of their business

Why is this the case? It may come down to predictability. Looking at your balance sheet is often easier to understand, and knowing exactly how much you are borrowing (and need to pay back) can allow the average business owner to formulate a plan that fits into their schedule. The equity model, on the other hand, can raise more questions and leave you wondering just how much of your business you’ll leave on the table.

Related Read: Is my money running out? Create a cash flow budget to find out

Make a comeback

Even if you stumble upon cash flow challenges, you can still make a comeback. Obtain your secret advantage by conducting a cash flow audit and updating your cash flow budget to accurately forecast your incoming and outgoing cash flow. Assess all the financing options available to determine which will be best at maintaining consistent cash flow to stay ahead of expenses. And of course, don’t be afraid to explore options beyond what a bank may have to offer.


To become the ultimate business survivor by making the most of alternative business funding, download The Invoice Factoring Guidebook now.


The invoice factoring guidebook download