A water dribble hitting the middle of a calm water gathering.

The Ripple Effect

As I work with companies in a variety of businesses, I generally focus on specific financing needs that run the gamut of scenarios; from high growth to high financial stress. My client is focused on addressing the company’s financing needs as it impacts company operations and seizing new business opportunities. At first glance, one could view the impact of acquiring the needed financing more narrowly. However, businesses are multifaceted, and the benefits extend throughout all aspects of the business and beyond, as well as positively impacting the U.S. economy as a whole.

Each party that interacts with a business is its own microcosm that has the same financial and operational needs. Whether it is a supplier, a customer, a building owner, an equipment provider or service provider, each has a vital interest in conducting business with companies that are financially stable and readily able to meet their financial obligations. In doing so, each party in turn can meet their own financial obligations as well.

The most poignant impact of a financially stable company is the ability to retain employees and attract desirable new employees. Every employee has their own set of financial obligations that need to be met. These would include paying their rent or mortgage payment, car payments, food, goods and services etc. Those providers in turn benefit and are able to address the financial and operational need of their business. The effects are felt further and further out into the economy. As in a single stone being thrown into a pond, the ripple effect generated spreads far beyond the point of initial impact. Given that small businesses constitute the vast majority of employers in the U.S., and correspondingly dramatically impact our overall economy, the value of companies having the requisite financing cannot be understated.

An important functional benefit is that when a company’s financing needs have been met, the business owner’s time and attention can be more readily focused on those issues that promote stability and growth versus being preoccupied and distracted with trying to find an answer to a financing shortfall. I have seen time and time again the emotional relief when this critical issue has been addressed.

I would welcome the opportunity to discuss my services with your clients and/or prospects as well as their far-reaching effects throughout their business.
An individual broken down on the side of the road with the hood of his car lifted.

Looking Under The Hood

The other day, I was thinking about the complexities of running a business and the many operational and financial components that must be in sync to truly optimize it success. As I thought about drawing a useful comparison, a gas powered car engine came to mind. Taken individually, each part of the engine contributes to its performance. However, if one or more of the parts does not operate properly, performance can be degraded, or worse yet, the engine can be seriously damaged. Critical to the operation of the engine of course is fuel. An unobstructed flow of fuel is the lifeblood of an engine. All components of the engine rely on the fuel to allow them to operate effectively and consistently. Conversely, any restriction of fuel will cause the engine to operate inefficiently, damaging parts and potentially causing the engine’s performance become erratic or to stop operating altogether. This comparison created many parallels as to the operation of a business and the critical role predictable cash flow plays in optimizing its performance.

While having predictable cash flow is seen as fundamental to the operation of a business, the ripple effects on all aspects of the business, not unlike the effects of fuel on the operation of the engine, bear further mention. The overall impact is that business decisions can be made, versus limitations and/or deferral due to undetermined receipt of payments by customers. These include:

  • Timely payment of suppliers – ability to take on more/larger orders and potential to negotiate discounts
  • Staying current with payables
  • Equipment leasing/purchase
  • Expanding facility or acquiring a new facility
  • Retaining/adding employees
  • Staying current on tax payments
  • Expanding marketing efforts
  • Engage needed advisors/consultants

While the above list is not all encompassing, it highlights the critical impact cash flow has on the business. An important by product is improved financial performance, ability to reduce debt and position the company to be a viable candidate for traditional financing or the ability to increase current financing availability. The result is a «high performance company hitting on all cylinders».

If your clients and/or prospects are experiencing «engine knock» in the operation of their business due to poor cash flow, I’d be happy to discuss a tune up and maximizing their financial MPG.

Just In Time – Just In Case

When a pressing need arises, we’re just in time. When planning for the future, we’re there…. just in case.

In working with a variety of clients, there have been numerous scenarios that called for using my financing services. They have run the gamut from seizing a sizable business opportunity to just keeping the doors open. In many instances, the timing was crucial, and we were “under the gun” to establish the account and start funding. In the alternative financing industry, these occurrences are common. However, it benefits all parties if a more time is available to address the issues on a proactive and strategic basis. While it may be a short term or “one off” financing need that we’re addressing, more often a longer-term integration of alternative financing is called for. That being the case, having time to assess the impact of predictable cash flow and the ability to confidently take on larger clients/orders aids in being able to make critical business decisions, many of which have been deferred due to the lack needed financing resources. Equally important, is the business owner’s ability to utilize those resources as they see fit. By being able to do so, the overall cost of the financing can be more effectively controlled.

At Liquid Capital, we utilize a business model that provides the business owner not only the needed financing but a level of discretion and flexibility to customize our services to their specific needs. Once a client’s customers are approved, our client can choose which customer, which invoice/s and the timing. Whatever the situation; a seasonal spike or lull in sales, a creditworthy but slow paying customer, a supplier needing a payment before shipping or an inordinately large order, the client can use our services as needed. Conversely, if there’s no current need, there is no requirement to use the financing nor any cost for not doing so. Being available as an “On Call” resource gives our clients confidence and comfort in conducting their business free from the frustration of second guessing when or if they’ll have needed cash flow.

This same flexibility benefits our banking partners. In working with a bank client, many times it’s only necessary to finance receivables of a select number of clients and specific invoices versus having the client finance all eligible invoices. This allows us to address the needs of the client while leaving the bank in a secure collateral position…. truly a win/win scenario.

“Success or failure in business is caused more by the mental attitude even than by mental capacities”. – Walter Scott

An eye watching an individual

Tom Stamborski Cash Flow Financing – “The Mind’s Eye”

No matter what stage of business you’re in, get ahead with Tom Stamborski Cash Flow Financing tips and business advice.

Tom Stamborski Cash Flow Financing

In working with various clients and prospects, beyond the strategic cash flow financing that I provide, the mindset of the business owner is an important factor that has to be taken into account. The business scenarios that create the need for my services cover a wide spectrum of circumstances. They run the gamut, from high growth to business survival.

Central to the situation is a triggering event that creates the need to enhance cash flow.

Can’t qualify for traditional bank financing?

For newer companies that currently don’t qualify for traditional bank financing, private assets are normally limited and operations progressively become strained. Suppliers demand upfront payments and restrictive terms. Customers prefer to stretch out their payables as they contend with their own business issues, creating an unpredictable cash flow stream. Continuance of this scenario puts many companies at risk during a very vulnerable period in their life cycle.

Need even more financing?

For high growth companies, a common problem is that, in many instances, their current bank is unable to increase the level of financing availability as rapidly as their growth would dictate. This, of course, is an unfortunate situation as their growth opportunities could catapult them to the next level of development.

Are there more options?

For companies that fall between these two scenarios, there are different variations. Due to industry downturns, poor management practices, internal disputes, etc., their financial statements reflect losses and weakening financial ratios. This can result in their financing availability being frozen, reduced or not renewed.

In the case of their current bank having capital issues, the result could be the bank asking the client to leave. As the situation intensifies, it logically puts increasing pressure on the business owner. As they become more fixated on finding a solution, they unfortunately are drawn away from important business activities, thereby exacerbating the problem. In many instances, by the time I’m called in to assist the prospective client, I’m providing a form of cash flow triage.

Tom Stamborski Cash Flow Financing: Helping you get ahead

As I’m able to implement a strategic plan to address and stabilize their cash flow needs, the corresponding benefit to the business owner is their ability to revisit important aspects of their business such as developing or refining their business plan, marketing and sales as well as expenses and profit margins. With predictable cash flow, they can confidently make the important business decisions so vital to their company.

Being in business is not a clinical exercise. It’s fraught with a range of emotions that run the spectrum, from bolstering a business owner’s confidence to a level of concern bordering on desperation. I’m gratified that I have been able to play a part in delivering the financial resources so crucial to the viability and growth potential of my client’s businesses. I’d welcome the opportunity to be of service to those prospects and clients where you deem my services to be appropriate.

“Greatness is not a function of circumstance. Greatness, it turns out, is largely a matter of conscious choice and discipline”. – Jim Collins

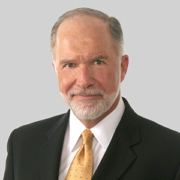
Headshot of Tom Stamborski

Tom Stamborski

Tom Stamborski is the president of Liquid Capital of Illinois, which helps small and mid-sized businesses with their alternative financing needs.

Born in Chicago, and a life-long resident of the Northwestern Suburbs, Tom is a finance specialist with career experience and expertise that spans more than four decades – and all of it in the financial services industry.

After attending Fresno State University and entering the financial services industry, Tom’s career path began to broaden. His tenure as a management executive was augmented in his capacity as a business owner and entrepreneur. Over the years, Tom has worked with individuals, business owners, and financial institutions, and has been involved in a diverse array of personal and business planning issues.

A strategic and analytical thinker, Tom is able to quickly decipher complex business scenarios and formulate incisive solutions, all the while working collaboratively with his clients. He is a genuine listener – a unique business attribute that allows for a full assessment before responding to client needs. After all, with a career of over 40 years behind you, one learns from those experiences – and providing better service to accommodate client’s needs becomes a priority.

As a Liquid Capital business owner, Tom fully understands the needs of other business owners. He brings a depth of understanding of the issues and challenges they face. But delivering a high level of service is just the beginning – building rapport with clients and developing viable business strategies completes the package.

Providing business financing and management direction, as well as responsive service are the key components of his full service approach to the client relationship, which Tom delivers to clients throughout the Midwest and beyond. This, along with a high level of communications with all related parties. But quick turnaround is another key element – because both business solutions AND financing are quickly initiated and implemented.

Married for 48 years, Tom’s wife Diana is also an entrepreneur, but in the training industry. Tom is a Vietnam veteran, having served in the Navy and is a member of the American Legion. He balances an active business life with sports and leisure activities that include physical fitness, tennis, fishing, and travel. His industry affiliations include the International Factoring Association, Secured Finance Network, Turnaround Management Association and Small Business Advocacy Council. Community involvement includes the McHenry Area Chamber of Commerce as a board member. Tom is also the Senior Vice Commander for American Legion Post 690 in Palatine, IL.

Tom’s charitable activities include St. Jude’s Children Hospital, Tunnel to Towers Foundation, The Wounded Warrior Project and The Humane Society of the United States.

Apply Now Form


Newsletter - Tom Stamborski